Form IR1480 Family-owned Investment Holding Vehicle Hong Kong
Guide to Form IR1480 for the statutory declaration of a family-owned investment holding vehicle in Hong Kong.
IR1480 at a glance
- Official title
- Statutory Declaration for Family-owned Investment Holding Vehicles
- Issued by
- Inland Revenue Department
We link the issuing authority's own index rather than hosting a copy, because the form is revised there and an out-of-date copy is worse than none.
Form IR1480 Family-owned Investment Holding Vehicle Hong Kong
Form IR1480 is a statutory declaration submitted to the Inland Revenue Department (IRD) by a family-owned investment holding vehicle (FIHV) seeking the concessionary profits tax rate under section 14C of the Inland Revenue Ordinance (Cap. 112). The form is lodged with the entity’s profits tax return (BIR51) for the year of assessment in which the concession is first claimed. The IRD uses the declaration to verify the vehicle meets the legislative eligibility criteria, such as the asset threshold and the prohibition on specified activities.
IR1480 Form Family Investment Vehicle: Eligibility Criteria
The IRD will only accept the declaration if the vehicle satisfies several conditions. The entity must be a corporation incorporated in Hong Kong or a non-Hong Kong company registered under Part 16 of the Companies Ordinance (Cap. 622). Throughout the basis period for the year of assessment, the vehicle must be a family-owned investment holding vehicle as defined in section 14C. This requires at least 90% of its issued shares, or a corresponding interest if it has no share capital, to be beneficially owned by a single family group. The family group comprises individuals connected by blood, marriage, adoption, or lineal descent, and may include trusts or other vehicles wholly owned by the family group.
The vehicle’s activities are restricted to holding and managing investments for the family group. It cannot carry on any trade or business in Hong Kong other than the “specified activities” permitted by the ordinance. These permitted activities are the acquisition, holding, management, and disposal of investments; the collection of investment income; and the payment of related incidental expenses. Engagement in trading, dealing, or any other commercial activity disqualifies the vehicle.
Hong Kong Family-owned Investment Vehicle: Asset Threshold and Income Test
To claim the concession, a Hong Kong family-owned investment vehicle must meet an asset threshold. At the end of the basis period, the total value of its assets must be at least HK$240 million, or another amount prescribed by the Financial Secretary by notice in the Gazette. This value is determined by reference to the vehicle’s most recent audited financial statements. If no audited statements are prepared, a certified true copy of accounting records that fairly present the asset position is required.
The income test is absolute. The vehicle’s gross income for the year must consist wholly of investment income derived from the specified activities. Investment income includes dividends, interest, rental income from investment property, capital gains on investment disposals, and other purely passive returns. Any incidental trading income, regardless of amount, disqualifies the vehicle. The IRD examines the nature of each income stream, not its quantum.
Inland Revenue IR1480: Declaratory Statements Required
Inland Revenue IR1480 requires a series of declaratory statements verified by an authorised person, typically a director, company secretary, or tax representative. The statements cover the vehicle’s legal name, business registration number, and tax file number. They confirm the vehicle is a family-owned investment holding vehicle as defined, with at least 90% beneficial ownership by the family group.
The declaration must state the vehicle did not carry on any trade or business beyond the specified activities during the basis period. It must also declare that the vehicle’s total assets at the end of the basis period met the HK$240 million threshold, supported by the relevant accounting records. The form requires confirmation that the vehicle’s gross income consisted wholly of investment income from the specified activities. Finally, the authorised person must acknowledge the vehicle will notify the IRD within 30 days if it ceases to meet any eligibility condition in a subsequent year.
The form must be signed by a person authorised to act for the vehicle. An undated or unsigned declaration will be rejected by the IRD, and the concession may be lost for that year.
Statutory Declaration Investment Vehicle: Supporting Documentation
A statutory declaration investment vehicle submission requires supporting documents. The IRD requires a certified true copy of the vehicle’s audited financial statements for the basis period, unless exempt from audit under section 141 of the Companies Ordinance (Cap. 622). Where no audit is required, the vehicle must provide a certified true copy of its management accounts or accounting records sufficient to verify the asset threshold and income composition.
If ownership is structured through a trust or another intermediate entity, the IRD may request the trust deed or the intermediate entity’s constitutional documents to confirm ultimate beneficial owners are within the family group. The vehicle should also be prepared to provide a schedule of the family group members, though this is not filed with the initial declaration unless requested.
Submission Procedure via the Business Tax Portal
Form IR1480 must be submitted with the profits tax return (BIR51) for the year of assessment in which the concession is first claimed. Submission is made through the Business Tax Portal on the IRD website, the mandated channel for electronic filing of profits tax returns for most corporate entities from the year of assessment 2025-26 onwards. Paper filing remains available for entities not required to file electronically, but the IRD encourages electronic submission for faster processing.
The vehicle should attach Form IR1480 as a supplementary document to the BIR51, along with the certified true copy of the financial statements and any other supporting schedules. The IRD will issue an acknowledgement of receipt and may later request further information. If the declaration is accepted, the vehicle is taxed at the two-tiered profits tax rates applicable to qualifying FIHVs: a concessionary rate on the first HK$2 million of assessable profits (subject to the standard two-tiered rates) and the standard rate on the remainder. The vehicle must retain a copy of the filed declaration and supporting documents for at least seven years after the relevant year of assessment.
The IRD’s Business Tax Portal is at https://www.ird.gov.hk/eng/tax/bus_epf.htm and the form itself is available from the IRD forms index at https://www.ird.gov.hk/eng/paf/bus.htm.
How to fill out Form IR1480
Page one of the official form. Every field named below appears on it in the same order.
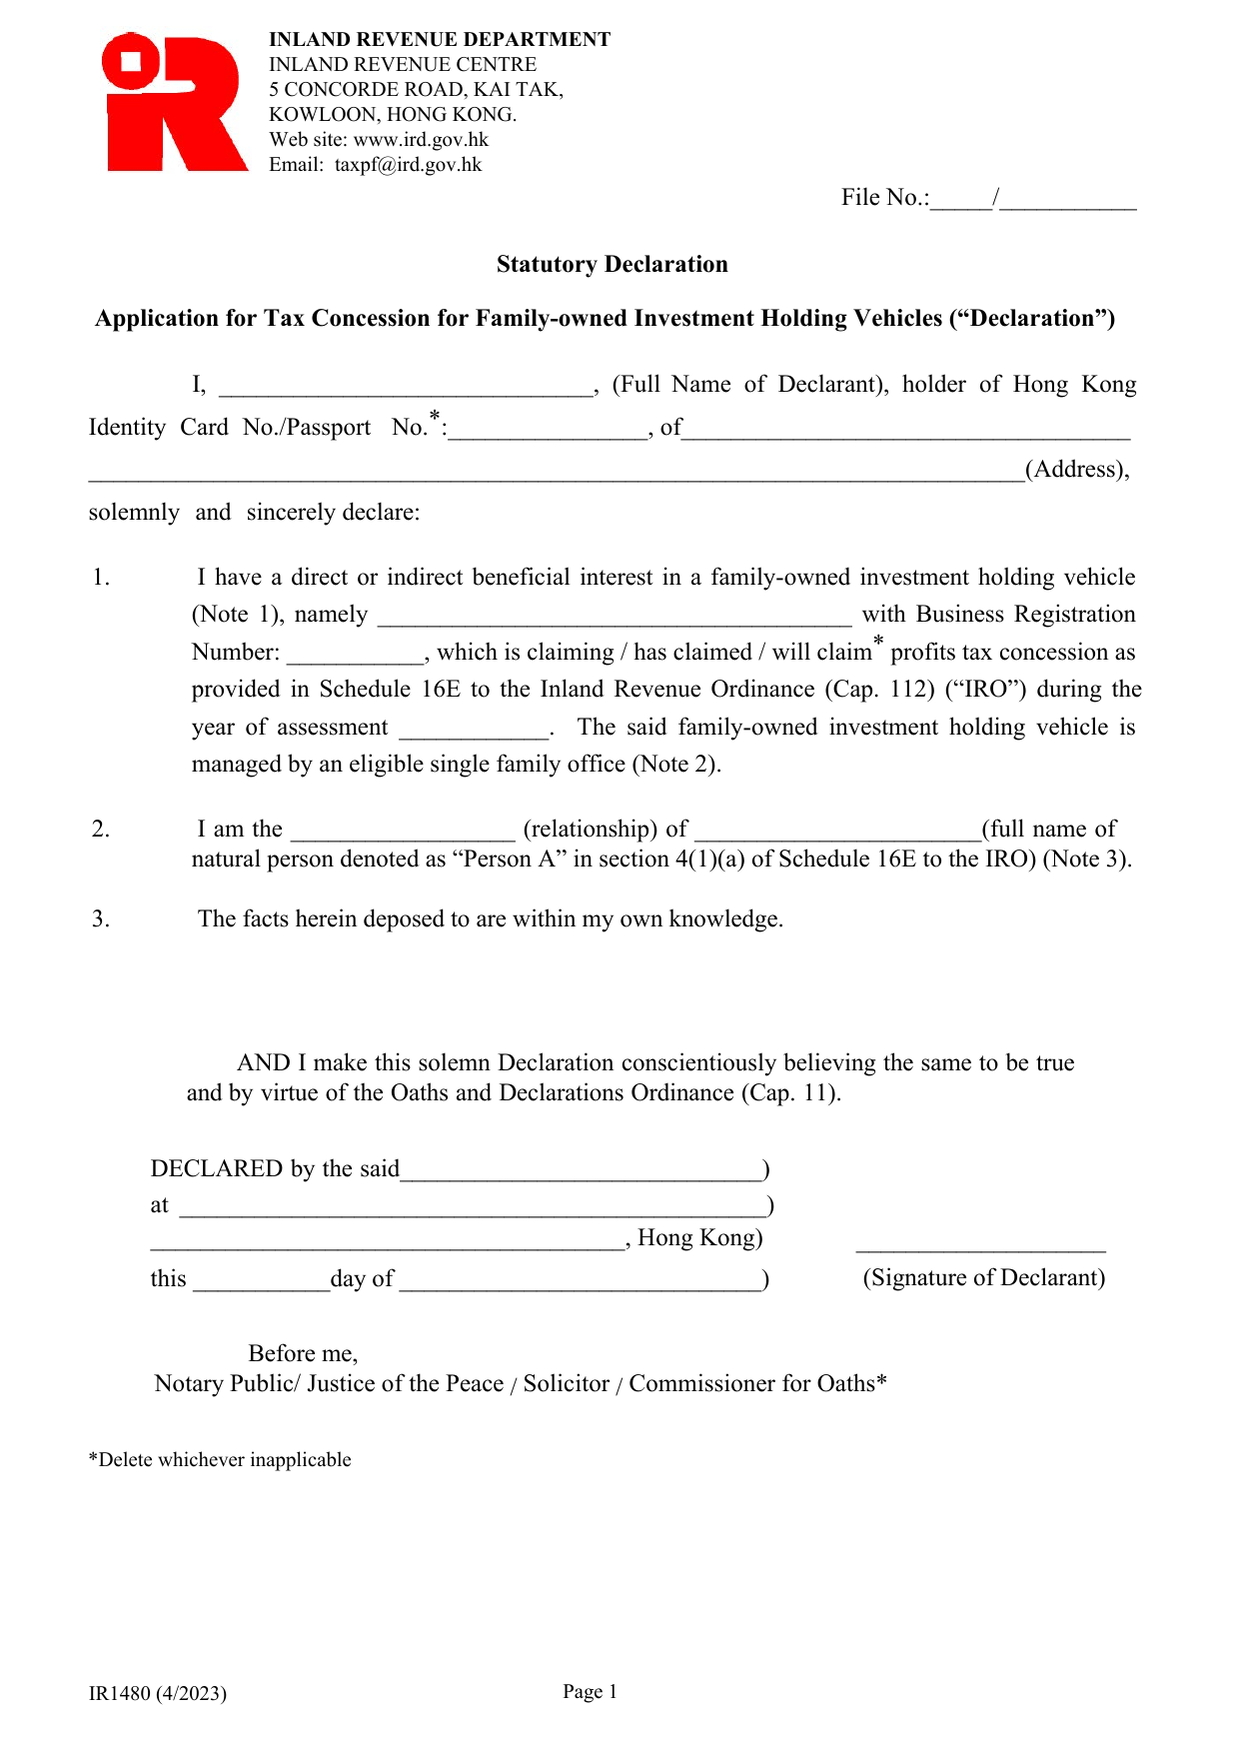
File No.
Enter the file number assigned by the Inland Revenue Department. If you do not yet have one, leave it blank; the Department will assign it.
Declarant Details
Full Name of Declarant: Your full name as it appears on your Hong Kong Identity Card or passport.
Hong Kong Identity Card No./Passport No.: Enter your HKID number or passport number. Delete the option that does not apply.
Address: Your residential or correspondence address.
Section 1: Family-owned Investment Holding Vehicle (FIHV)
Name of FIHV: The full legal name of the entity that is claiming, has claimed, or will claim the profits tax concession under Schedule 16E of the Inland Revenue Ordinance.
Business Registration Number: The entity’s Business Registration number. This is found on the Business Registration Certificate issued by the Inland Revenue Department.
Year of Assessment: The year of assessment for which the concession is claimed (e.g., 2023/24).
Section 2: Relationship to Person A
Relationship: Your relationship to the natural person referred to as “Person A” in section 4(1)(a) of Schedule 16E. Examples include spouse, child, father, mother, brother, or sister. See Note 3 of the form.
Full Name of Person A: The full name of the natural person who is the designated “Person A” for the family.
Section 3: Declaration of Knowledge
This section is a standard statement that the facts are within your own knowledge. No entry is required.
Declaration Block
Declared by the said: Repeat your full name as it appears at the top of the form.
At: The location where the declaration is made (e.g., the name of the city and the specific office or place).
This __ day of ____: The date you sign the declaration.
Signature of Declarant: Your signature, made in the presence of the authorised officer.
Before Me (Commissioner for Oaths)
Notary Public / Justice of the Peace / Solicitor / Commissioner for Oaths: The authorised officer who witnesses your signature must sign here and delete the options that do not apply. This person must be one of the listed categories.
Common mistakes: Ensure the year of assessment in Section 1 matches the period for which the FIHV is claiming the concession. The relationship in Section 2 must be directly to “Person A,” not to the FIHV itself. The declarant must be a family member who holds a beneficial interest in the FIHV.
Download the current form - always file the version on the issuing authority's site, not a copy.
Sources
More on the forms library.