Form IR1360A instalment application for partnerships
Learn how partnerships can apply for tax instalments in Hong Kong with our detailed guide to completing Form IR1360A.
IR1360A at a glance
- Official title
- Instalment Application for Partnerships
- Issued by
- Inland Revenue Department
We link the issuing authority's own index rather than hosting a copy, because the form is revised there and an out-of-date copy is worse than none.
Understanding Form IR1360A Instalment Application for Partnerships
Form IR1360A lets partnerships pay tax by instalments. It differs from the corporate version, Form IR1360B, because partnership tax is assessed on the business but the liability falls on the individual partners. Use this form to propose a payment schedule when the partnership cannot settle the full tax liability by the due date.
Partnership Tax Instalment Hong Kong
Hong Kong partnerships pay profits tax on business income. The Inland Revenue Department issues a single assessment notice, yet each partner is jointly and severally liable for the tax. A partnership unable to pay in full by the due date may apply for a payment plan. The Inland Revenue Ordinance (Cap. 112) gives the Commissioner discretion to allow instalments where the partnership demonstrates genuine financial hardship.
Apply before the tax due date. Late applications are rarely accepted without proof of exceptional circumstances. The IRD reviews each application on its merits, considering the partnership's finances, the tax owed and the proposed repayment schedule.
IRD Form IR1360A
Form IR1360A is the official application document from the Inland Revenue Department. Download it from the IRD website's forms index. The form requires detailed information on the partnership's business, partners and financial circumstances. Complete all relevant sections accurately; incomplete applications are rejected without consideration.
The form is structured in parts. Part A requests partnership particulars: business name, business registration number and tax file number. Part B needs details of the tax liability, including the year of assessment and amount due. Part C is the financial assessment, where the partnership explains why it cannot pay in full and provides evidence of its financial position.
Hong Kong Partnership Tax Payment Plan
A successful application results in a Hong Kong partnership tax payment plan. The IRD considers the partnership's proposal and may offer a schedule of monthly or quarterly payments. The plan usually requires full payment within a reasonable period, not exceeding 12 months. The IRD may request more information or documentation before approving the plan.
The partnership must continue paying its current tax obligations while the instalment plan is active. Missing a payment can cause the IRD to revoke the plan and demand immediate payment of the outstanding balance. The IRD may also charge interest on overdue tax, even during an instalment plan.
Apply for Tax Instalments Partnership
To apply, complete Form IR1360A and submit it to the Inland Revenue Department with supporting documents. These documents should prove the partnership's financial position, such as recent financial statements, bank statements, cash flow projections and details of other liabilities. Include a letter explaining why payment is not possible and proposing a specific repayment schedule.
Send the application to the IRD's office. Keep a copy of the application and all correspondence for your records. The IRD will acknowledge receipt and may ask for more information. Respond promptly to any queries to avoid processing delays.
Partnership Provisional Tax Instalment
Partnership provisional tax instalment applications apply when a partnership faces a provisional tax assessment. Provisional tax is an advance payment based on the previous year's profits. If the partnership expects significantly lower profits, it may apply for a holdover of provisional tax using Form IR1121. If it cannot pay the assessed provisional tax, it may use Form IR1360A to request instalments.
Applying for instalments does not change the obligation to file the profits tax return on time. The partnership must still submit its return and pay any tax due according to the approved schedule. The IRD may review the partnership's compliance history when considering the application, so a record of timely filings is beneficial.
Information Required on the Form
Form IR1360A requires comprehensive information. The partnership particulars section needs the business name, business registration number, correspondence address and nature of the business. You must also provide the tax file number and the year of assessment for which instalments are sought.
The financial assessment section is the most detailed. State the total tax due, the amount payable immediately and the proposed instalment amounts and dates. Explain the reasons for financial difficulty, such as a business downturn, unexpected expenses or delayed customer receipts. You must also provide details of assets, liabilities, income and expenses.
Partner Details
The form requires details for every partner. Provide each partner's name, Hong Kong identity card number or passport number and correspondence address. Indicate whether each partner is an individual or a corporation. If a partner is a corporation, give its business registration number and place of incorporation.
The IRD uses this information to verify partner identities and assess their individual financial positions. Because partners are jointly and severally liable, the IRD may consider their personal finances when evaluating the application. Ensure all partner details are accurate and current.
Application Submission
Submit the completed Form IR1360A and supporting documents to the Inland Revenue Department. The form can be sent by post or delivered in person to the IRD office. Electronic submission through the eTAX system is not currently accepted. Allow several weeks for the IRD to review the application.
Submit the application as early as possible, ideally at least 14 days before the tax due date. The IRD may still consider a late application if you provide a good reason for the delay, but do not assume it will be accepted. The IRD may impose conditions, such as requiring a deposit or a partner's guarantee.
After Approval
After approval, the partnership must strictly follow the payment schedule. The IRD will issue a notice of approval with the plan's terms, including each instalment's amount and due date. Make each payment on time using an approved method, such as bank transfer, autopay or cheque.
If the partnership's finances improve, it can pay the outstanding balance early without penalty. If finances worsen, it may apply for a variation by submitting a new application. Contact the IRD immediately if you anticipate difficulty meeting the payment schedule.
How to fill out Form IR1360A
Page one of the official form. Every field named below appears on it in the same order.
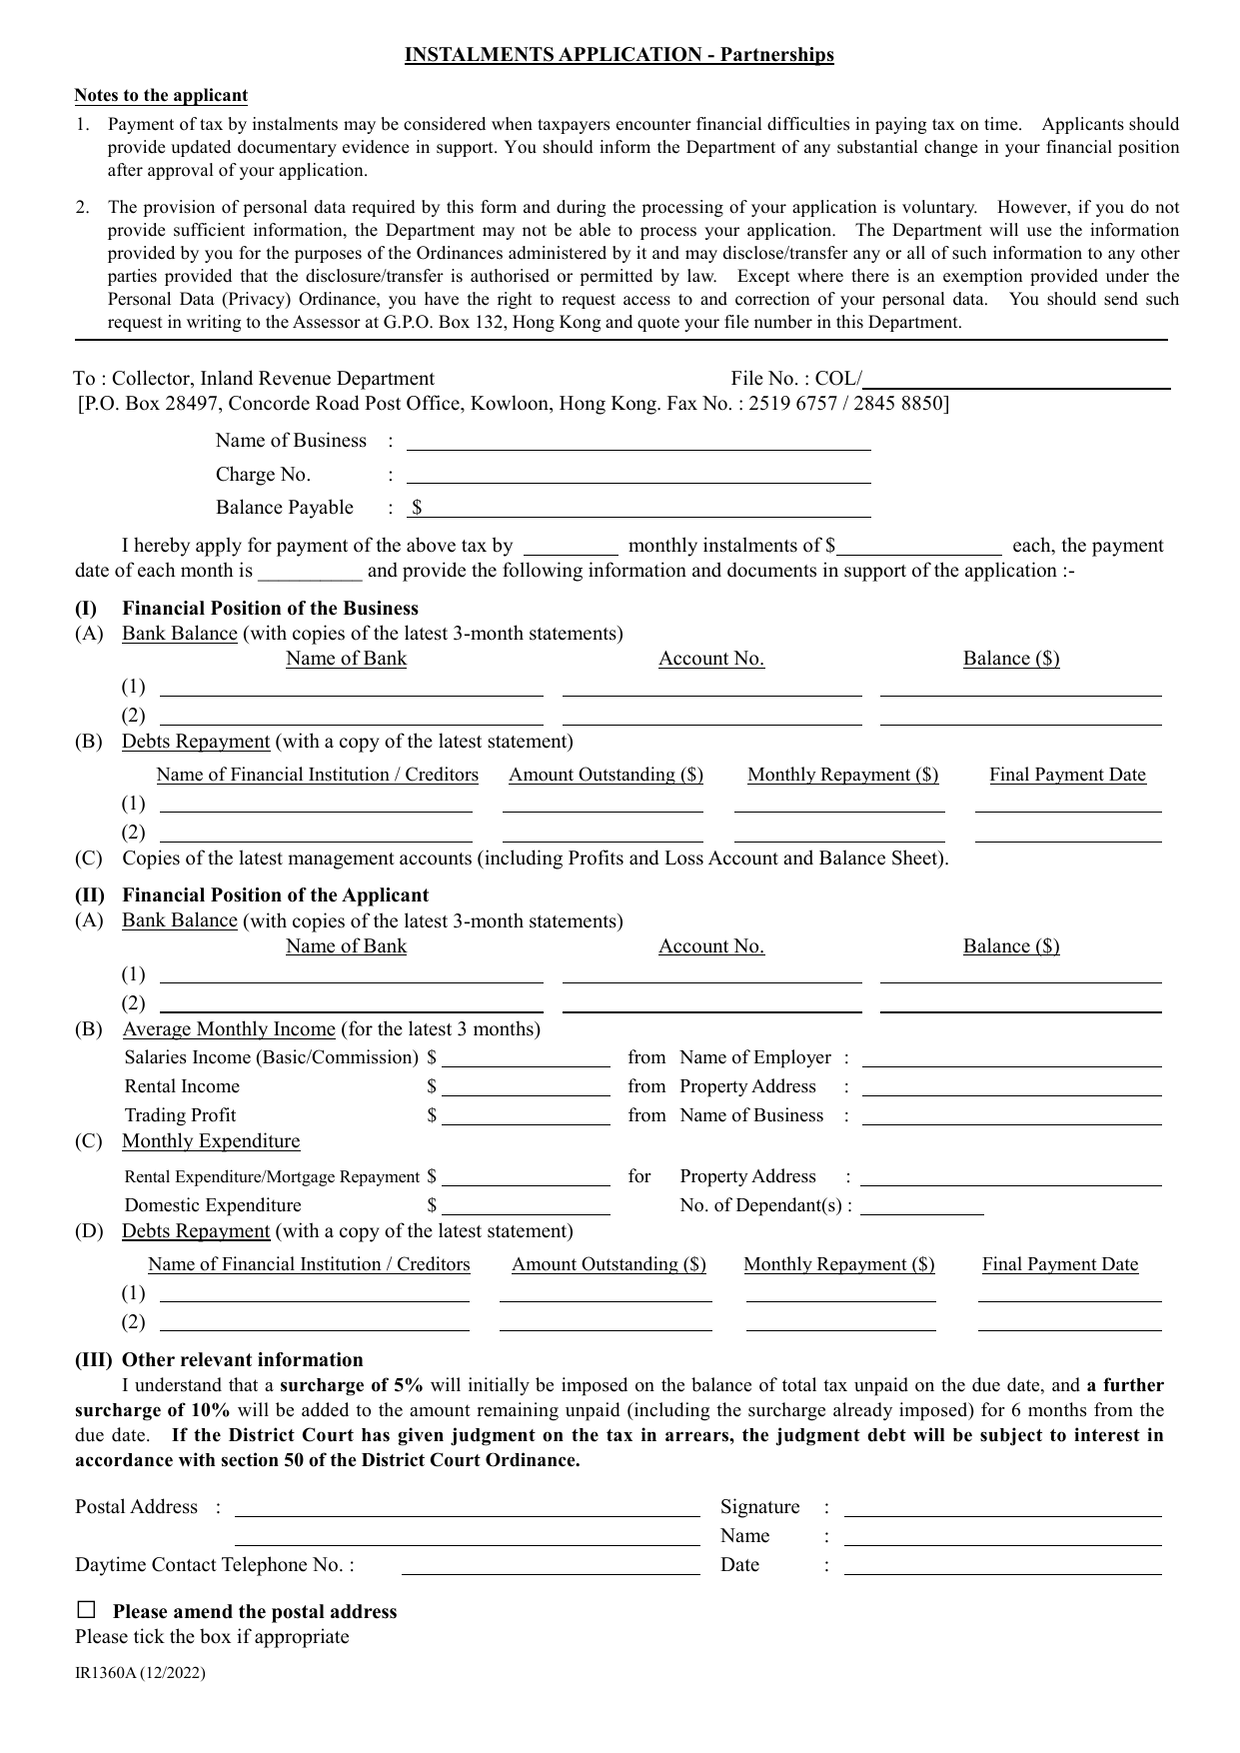
To : Collector, Inland Revenue Department / File No. : COL/
Enter the file number assigned by the Inland Revenue Department. If you do not have one, leave it blank; the Department will assign one.
Name of Business / Charge No. / Balance Payable
- Name of Business: The full registered business name exactly as it appears on the Business Registration certificate.
- Charge No.: The tax assessment charge number shown on the demand note or tax bill you are applying to pay by instalments.
- Balance Payable: The total amount of tax still unpaid as shown on the demand note. Enter the figure in Hong Kong dollars.
Instalment Proposal
State the number of monthly instalments you are requesting (e.g., "6") and the amount of each instalment. Then fill in the payment date of each month (e.g., "15th"). The first instalment date must be a date after the Department approves the application.
(I) Financial Position of the Business
(A) Bank Balance: List the business bank accounts. Provide the name of the bank, account number, and current balance. Attach copies of the latest 3 months' bank statements for each account.
(B) Debts Repayment: List any loans or credit the business owes. For each creditor, enter the total amount outstanding, the monthly repayment amount, and the final payment date. Attach a copy of the latest statement from each creditor.
(C) Copies of the latest management accounts: Attach the most recent profit and loss account and balance sheet for the business. If none exist, explain why in a separate note.
(II) Financial Position of the Applicant
This section is for the individual partner(s) who are liable for the tax. If there are multiple partners, each should complete a separate IR1360A or attach a continuation sheet.
(A) Bank Balance: List your personal bank accounts. Provide bank name, account number, and balance. Attach copies of the latest 3 months' statements.
(B) Average Monthly Income: For the latest 3 months, enter: - Salaries Income: Basic salary and commission, plus employer name. - Rental Income: Monthly rent received, plus property address. - Trading Profit: Monthly profit from the business, plus business name.
(C) Monthly Expenditure: - Rental Expenditure/Mortgage Repayment: Monthly amount for your home, plus property address. - Domestic Expenditure: Monthly household expenses, plus number of dependants.
(D) Debts Repayment: List personal loans. For each creditor, enter amount outstanding, monthly repayment, and final payment date. Attach the latest statement.
(III) Other Relevant Information
Use this space to explain any special circumstances, such as a sudden drop in income, medical expenses, or business losses. The surcharge notice is printed on the form for your reference; do not fill it in.
Postal Address / Signature / Name / Date
- Postal Address: Your correspondence address. If it differs from the one the Department holds, tick the "Please amend the postal address" box.
- Signature: The partner(s) who signed the tax return must sign here. If the partnership has a designated partner, that person signs.
- Name: Print the full name of the signatory.
- Date: The date you sign the form.
Common mistake: Dates in Section (I) and (II) must match the attached bank statements and management accounts. Do not leave any balance or amount blank; if zero, write "0".
Download the current form - always file the version on the issuing authority's site, not a copy.
Sources
More on the forms library.