Form IRSD121 Adjudication or Stamping Request Intra-Group Assignment
Use Form IRSD121 for adjudication or stamping of intra-group assignments in Hong Kong. Learn the requirements and how to apply for relief.
IRSD121 at a glance
- Official title
- Adjudication or Stamping Request for an Intra-Group Assignment
- Issued by
- Inland Revenue Department
We link the issuing authority's own index rather than hosting a copy, because the form is revised there and an out-of-date copy is worse than none.
Form IRSD121 Adjudication or Stamping Request for Intra-Group Assignment
Understanding Intra-Group Assignments and Stamp Duty Relief
An intra-group assignment transfers Hong Kong immovable property between companies within the same corporate group. Such transfers may qualify for stamp duty relief under section 45 of the Stamp Duty Ordinance (Cap. 117). This relief exempts the transaction from ad valorem stamp duty, lowering the cost of corporate restructuring.
Apply for this relief using Form IRSD121 Adjudication or Stamping Request for Intra-Group Assignment. Submit it to the Inland Revenue Department (IRD) Stamp Office to either adjudicate the duty payable or have the instrument stamped with the intra-group exemption.
To qualify, the transferor and transferee must be associated companies at the time of assignment. One company must be the beneficial owner of at least 90% of the other's issued share capital, or a third company must beneficially own at least 90% of both. The consideration must not come from outside the group, and the instrument must be executed solely for this intra-group transfer.
If relief applies, no ad valorem duty is due. A fixed duty of HK$100 is payable instead. If relief is unavailable, the Stamp Office will adjudicate duty based on the consideration or market value, whichever is higher.
IRSD121 Intra-Group Assignment Stamping
"IRSD121 intra-group assignment stamping" describes using this form to get the assignment instrument officially stamped. Stamping is the Stamp Office's act of marking the document to confirm duty is paid or an exemption applies.
Complete Part A (Adjudication or Stamping Request) and Part B (Particulars of the Instrument) of Form IRSD121. You will need the instrument's date, the parties' names and addresses, the property description, and the consideration paid.
Supporting documents are mandatory. Provide a copy of the assignment instrument, the latest annual returns for both companies, and proof of the group structure. This proof includes share registers, certificates of incorporation, and shareholding statements showing the 90% ownership link. If a third company holds 90% of both parties, submit its documentation as well.
A director, company secretary, or authorised representative of the transferee must sign the declaration. This confirms the conditions for relief under section 45 of the Stamp Duty Ordinance (Cap. 117) are met. The signatory must have the authority to bind the company.
Time Limits for Stamping
Stamping deadlines are strict. An instrument executed in Hong Kong must be presented for stamping within 30 days of execution. For instruments executed outside Hong Kong, the deadline is 40 days after it arrives in Hong Kong. Late stamping incurs penalties. The penalty is the higher of HK$100 or 10% of the unpaid duty for delays up to one month, and the higher of HK$200 or 20% of the unpaid duty for longer delays. These penalties apply even if relief is ultimately granted, so submit Form IRSD121 promptly.
When Relief May Be Withdrawn
The Stamp Office can withdraw relief if the property leaves the group too soon. Under section 45(4) of the Stamp Duty Ordinance (Cap. 117), if the transferee ceases to be associated with the transferor within two years, or if the property is transferred outside the group in that time, the relief is revoked. The transferee must then pay the ad valorem duty that would have been due on the original assignment, plus interest. This clawback prevents abuse of the relief for short-term arrangements.
Adjudication Vs. Stamping
The form lets you request either adjudication or stamping. Adjudication is the Stamp Office's process to determine the correct duty. When claiming the intra-group exemption, you usually request adjudication to confirm the relief applies. Stamping without adjudication is only appropriate if you are certain of eligibility and are paying the fixed HK$100 duty. Most applicants seek adjudication to obtain certainty.
Practical Considerations
Before filing, verify the group structure. The 90% beneficial ownership test must be met at the time of assignment. Recent structural changes may require extra evidence. The Stamp Office may ask for more information, so allow time for follow-up.
The form is on the IRD website. Submit it in person or by post to the Stamp Office. There is no filing fee, but the fixed HK$100 duty is payable on stamping. If relief is denied, you must pay the adjudicated ad valorem duty before the instrument is stamped.
Seek professional advice for complex group structures, assignments of multiple properties, or any uncertainty about eligibility. Form errors or missing documents cause delays and may trigger penalties.
Stamp Intra-Group Assignment HK
The process to stamp intra-group assignment HK transactions relies on Form IRSD121. The Stamp Office reviews the application to confirm the transaction meets the criteria for relief. If the application is successful, the assignment instrument is stamped to show the exemption from ad valorem stamp duty applies. The fixed HK$100 duty is paid to finalise the stamping.
How to fill out Form IRSD121
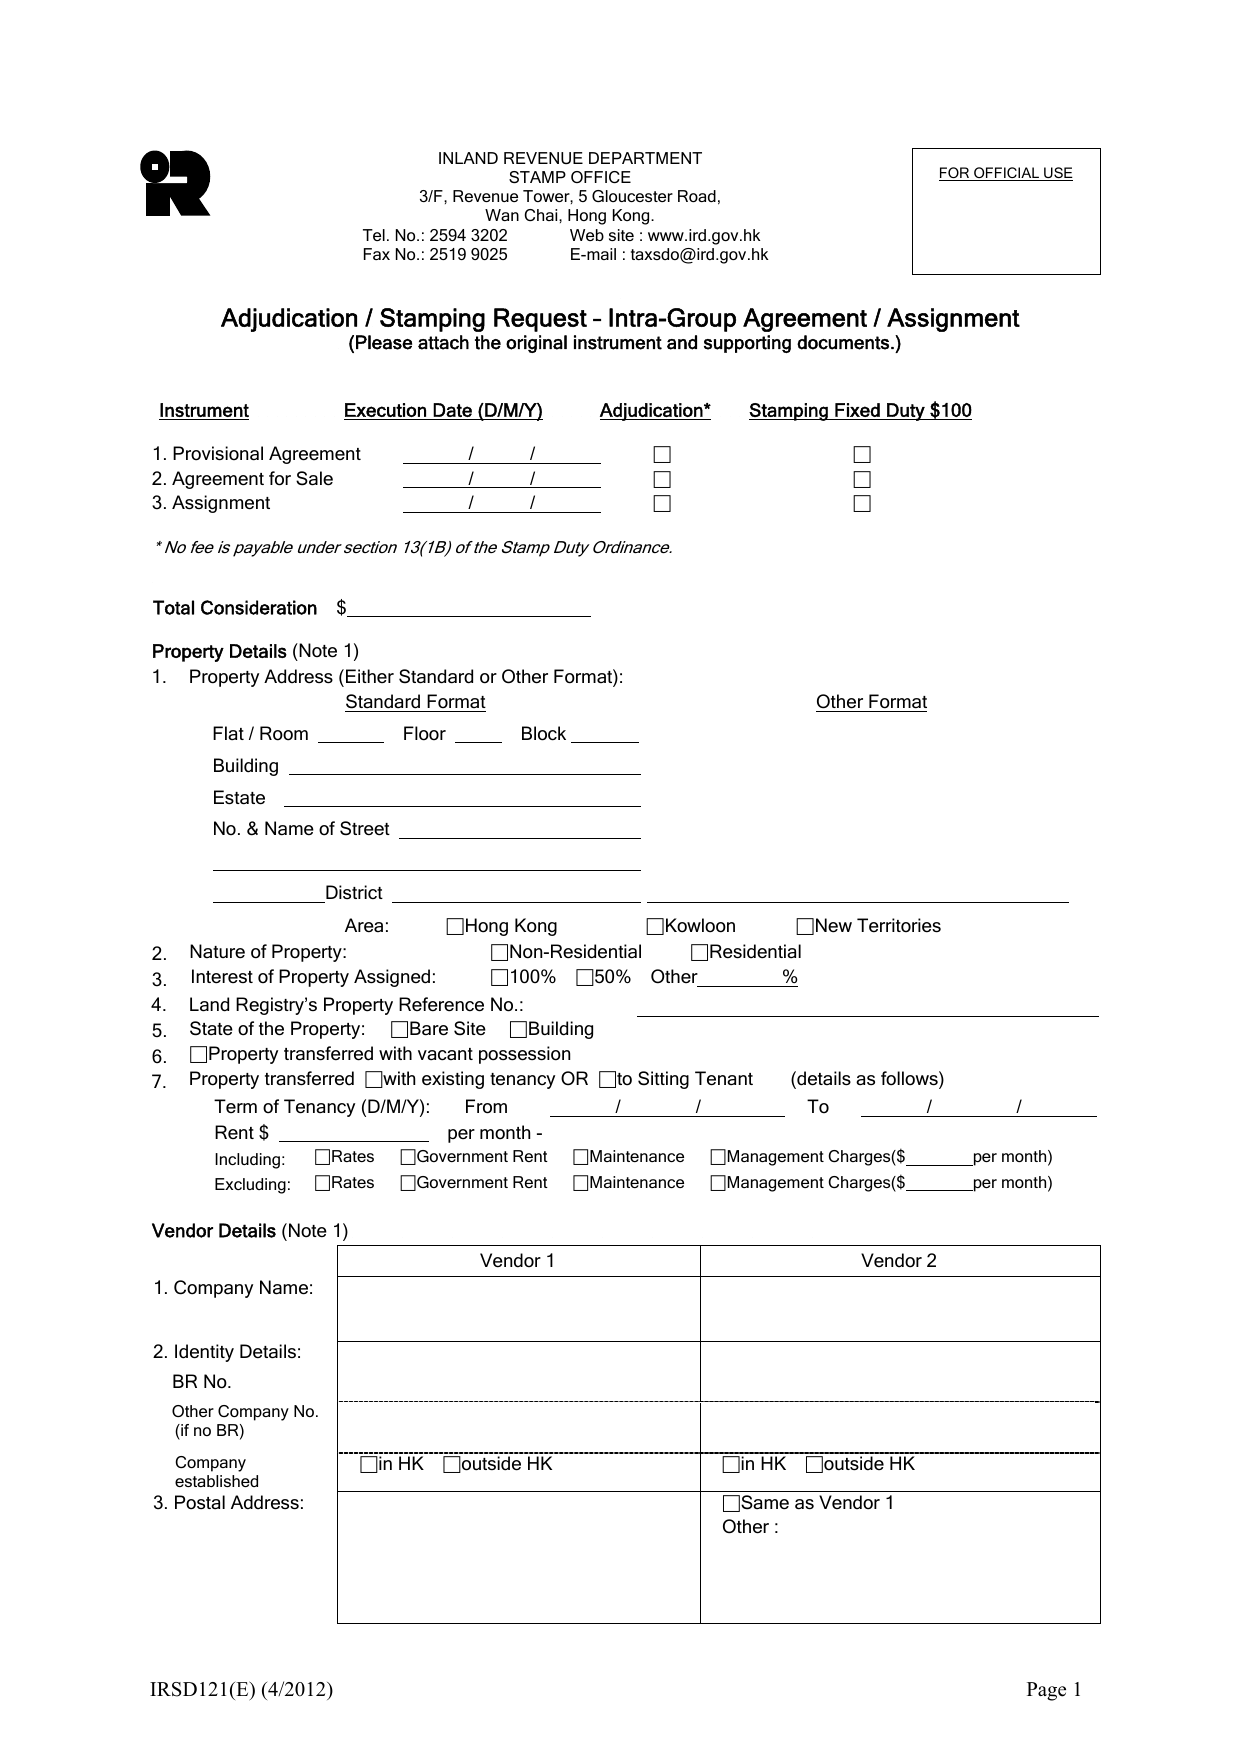
Page one of the official form. Every field named below appears on it in the same order.
Instrument, Execution Date, Adjudication, Stamping
List each instrument you are presenting for adjudication or stamping. For each row, enter the Execution Date in day/month/year format (the date the instrument was signed). In the Adjudication column, tick the box if you are requesting adjudication (no fee is payable under section 13(1B) of the Stamp Duty Ordinance for this). In the Stamping Fixed Duty $100 column, tick the box if the instrument qualifies for the fixed $100 duty and you are requesting that. You may tick both boxes or only one. The three instruments are: 1. Provisional Agreement 2. Agreement for Sale 3. Assignment
Total Consideration
Enter the total consideration for the intra-group assignment in Hong Kong dollars.
Property Details
- Property Address: Complete either the Standard Format (Flat/Room, Floor, Block, Building, Estate, No. & Name of Street, District) or the Other Format box. Tick Hong Kong, Kowloon, or New Territories for the area.
- Nature of Property: Tick Non-Residential or Residential.
- Interest of Property Assigned: Tick 100%, 50%, or write the exact percentage in “Other %”.
- Land Registry’s Property Reference No.: The property reference number from the Land Registry.
- State of the Property: Tick Bare Site or Building.
- Tick if the property is transferred with vacant possession.
- If transferred with existing tenancy or to Sitting Tenant, tick the appropriate box and provide: - Term of Tenancy: From and To dates. - Rent per month. - Tick items included in rent (Rates, Government Rent, Maintenance, Management Charges) and enter the management charges amount if known. - Tick items excluded from rent.
Vendor Details
For Vendor 1 and, if applicable, Vendor 2: 1. Company Name: Full legal name. 2. Identity Details: Enter the BR No. (Business Registration number). If no BR, enter the Other Company No. Tick whether the company is established in HK or outside HK. 3. Postal Address: For Vendor 2, you may tick “Same as Vendor 1” or write an address in “Other”.
Purchaser Details
For Purchaser 1 and, if applicable, Purchaser 2: 1. Company Name: Full legal name. 2. Identity Details: Follow the same rules as for Vendor Details. 3. Postal Address: Tick Property Address to use the property address, or tick Same as Purchaser 1 for Purchaser 2, or write an address in “Other”. 4. Share Assigned: Tick Sole-owner or Joint-owner for Purchaser 1; for Purchaser 2, tick Joint-owner or Co-owner and write the percentage. The total percentage of co-owners must equal the percentage entered in Property Details item 3.
Declaration, Signature, and Date
Read the declaration. The signatory must sign, date, print their name, and state their Capacity: Vendor, Purchaser, Legal Representative, or Other. Provide an Address, Contact Reference No., Telephone No., and Fax No. An organization chop is required. Tick the final box if applicable.
Notes
If space is insufficient for any section, attach details on a separate sheet.
Download the current form - always file the version on the issuing authority's site, not a copy.
Sources
More on the forms library.