Applying for a company resident status certificate with Form IR1313A
Apply for a Certificate of Resident Status for your Hong Kong company using Form IR1313A to claim treaty benefits.
IR1313A at a glance
- Official title
- Application for Certificate of Resident Status for a Company or Partnership
- Issued by
- Inland Revenue Department
We link the issuing authority's own index rather than hosting a copy, because the form is revised there and an out-of-date copy is worse than none.
Form IR1313A Company Resident Status Certificate
A company seeking to claim benefits under a double taxation agreement must first obtain a Certificate of Resident Status from the Inland Revenue Department. The Form IR1313A company resident status certificate is the application used by companies and partnerships to request this document, which confirms the entity is resident in Hong Kong for tax purposes.
Certificate of Resident Status Company Hong Kong
A certificate of resident status for a company in Hong Kong is an official letter issued by the Inland Revenue Department (IRD). It certifies that the applicant company is a Hong Kong resident for the purposes of a specific double taxation agreement (DTA). The certificate is typically required by the tax authority in the other treaty jurisdiction before the company can claim reduced withholding tax rates or exemption from tax in that jurisdiction. The IRD issues the certificate based on the information provided in the application and its own records.
IR1313A Application Requirements
The application requirements for Form IR1313A are set by the Inland Revenue Department. The applicant must complete the form in full, providing the following particulars:
- The company's name, business registration number, and Hong Kong address.
- The date and place of incorporation.
- The nature of the business operations carried on in Hong Kong.
- Details of the place where central management and control is exercised.
- The double taxation agreement under which the certificate is sought.
- The period for which the certificate is requested (usually a specific year of assessment).
The form must be signed by a director, company secretary, or other authorised person. The IRD may request additional information if the application is incomplete or unclear.
Tax Residency Certificate Hong Kong Company
A tax residency certificate for a Hong Kong company is not automatically granted. The IRD assesses whether the company is resident in Hong Kong under the relevant double taxation agreement. The key criterion is usually the place of central management and control. A company is generally considered resident in Hong Kong if its central management and control is exercised in Hong Kong. This means the board of directors meets in Hong Kong, strategic decisions are made in Hong Kong, and the company's key officers are based in Hong Kong. The IRD will examine the company's structure, operations, and governance to determine residency.
Supporting Documents for the Application
The applicant must submit supporting documents with Form IR1313A. These typically include:
- A certified true copy of the company's Certificate of Incorporation.
- A certified true copy of the company's Business Registration Certificate.
- A copy of the company's annual return (Form NAR1) filed with the Companies Registry.
- A copy of the company's audited financial statements for the relevant period.
- A copy of the board minutes showing where board meetings are held.
- A copy of the company's tax return (Form BIR51) and tax assessment for the relevant year.
The IRD may request certified true copies of other documents, such as employment contracts, lease agreements, or bank statements, to verify the company's presence and activities in Hong Kong.
Fees and Processing Time
The Inland Revenue Department does not charge a fee for processing Form IR1313A. However, the applicant should check the IRD's website for any updates to the fee structure. The processing time varies depending on the complexity of the application and the completeness of the supporting documents. The IRD generally aims to process applications within four to six weeks, but complex cases may take longer.
Criteria the IRD Uses to Determine Tax Residency
The IRD applies the following criteria when determining whether a company is resident in Hong Kong for treaty purposes:
- Place of central management and control: Where the board of directors meets and makes strategic decisions.
- Place of incorporation: Hong Kong incorporation is a factor but not determinative.
- Place of business operations: Where the company's day-to-day activities are carried out.
- Place of effective management: Where the company's key personnel are based and where management decisions are implemented.
The IRD will issue the certificate only if it is satisfied that the company is resident in Hong Kong under the relevant DTA. If the company is not resident, the IRD will refuse the application and may provide reasons.
Renewal and Validity
A Certificate of Resident Status is typically issued for a specific year of assessment. The company must submit a new Form IR1313A for each subsequent year it needs the certificate. The certificate is valid only for the period stated on it. The IRD may issue a certificate for multiple years if the company's circumstances have not changed, but this is at the department's discretion.
Where to Submit the Application
The completed Form IR1313A and supporting documents must be submitted to the Inland Revenue Department. The form is available on the IRD's website. The applicant should send the application to the address specified in the form's instructions. The IRD may request the applicant to submit the application through the Tax Representative Portal if the company is represented by a tax representative.
Common Reasons for Rejection
The IRD may reject an application for a Certificate of Resident Status if:
- The company does not have central management and control in Hong Kong.
- The company is dormant or has no business operations in Hong Kong.
- The application is incomplete or the supporting documents are insufficient.
- The company is not resident in Hong Kong under the relevant DTA.
Applicants should ensure the application is complete and accurate to avoid delays or rejection.
How to fill out Form IR1313A
Page one of the official form. Every field named below appears on it in the same order.
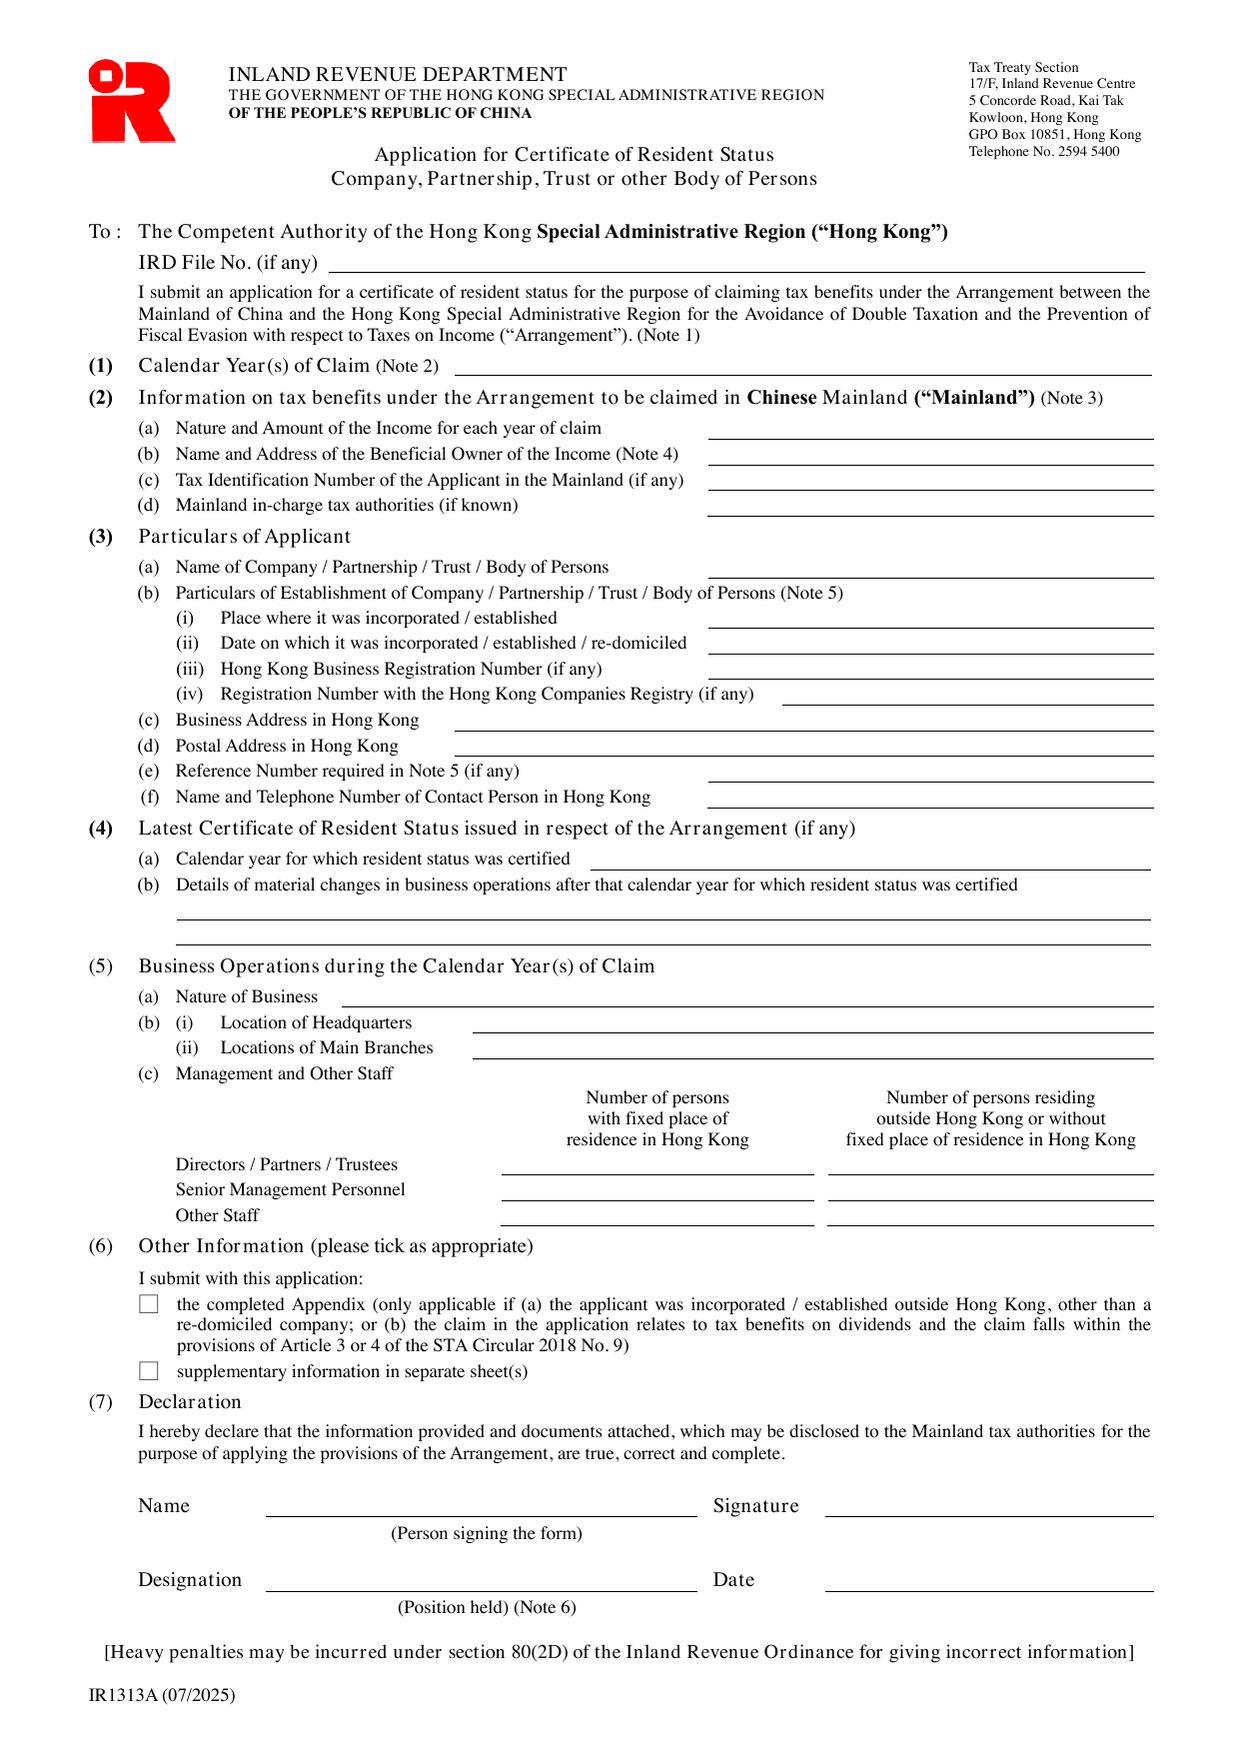
(1) Calendar Year(s) of Claim (Note 2)
Enter the calendar year (e.g., 2024) for which resident status is sought. A certificate for one year generally serves as proof for that year and the two succeeding years, so you may not need to reapply for consecutive years. If circumstances change after the certified year, the certificate will no longer apply.
(2) Information on Tax Benefits under the Arrangement to be Claimed in Mainland (Note 3)
- Nature and Amount of the Income for each year of claim: Describe the income type (e.g., dividends, interest) and the amount for each year listed in (1).
- Name and Address of the Beneficial Owner of the Income (Note 4): If the applicant is not the beneficial owner (e.g., nominee or conduit), provide the actual owner’s details. For dividends under STA Circular 2018 No. 9, if the immediate recipient is deemed beneficial owner under Article 3, provide the name and address of the person who holds directly or indirectly 100% equity in that recipient.
- Tax Identification Number of the Applicant in the Mainland (if any): If the applicant has a Mainland TIN, enter it.
- Mainland in-charge tax authorities (if known): The local tax bureau that handles the claim.
(3) Particulars of Applicant
- Name: Full legal name of the entity.
- Place of incorporation/establishment: City and country.
- Date of incorporation/establishment/re-domicile: Exact date, matching the certificate.
- Hong Kong Business Registration Number: From the BR certificate.
- Registration Number with Hong Kong Companies Registry: From the Certificate of Incorporation (CR number).
- Business Address in Hong Kong: Physical operational address.
- Postal Address in Hong Kong: Mailing address, if different.
- Reference Number from Note 5 (if any): If you have previously submitted the required documents (listed in Note 5) under another application, provide that application’s reference number here to avoid re-submission.
- Contact person: Name and phone number of someone in Hong Kong who can answer IRD queries.
(4) Latest Certificate of Resident Status Issued (if any)
- Calendar year certified: The year of any previous certificate.
- Details of material changes: Describe any changes in business operations since that year (e.g., new locations, staff changes) that affect resident status.
(5) Business Operations during the Calendar Year(s) of Claim
- Nature of Business: Brief description of principal activities.
- Location of Headquarters: Street address of central management.
- Locations of Main Branches: Physical addresses of key branches.
- Staff Table:
- Directors / Partners / Trustees
- Senior Management Personnel
- Other Staff For each category, count:
- Number with fixed place of residence in Hong Kong
- Number residing outside Hong Kong or without fixed residence in Hong Kong
(6) Other Information
Tick the applicable box(es): - The completed Appendix (required if the applicant was incorporated/established outside Hong Kong, or the claim is for dividends under STA Circular 2018 No. 9, Articles 3 or 4). - Supplementary information on separate sheets (if needed).
(7) Declaration
The form must be signed by a person authorised under Note 6: - Company: director, secretary, or manager - Partnership (other than LPF): precedent partner - Limited partnership fund: general partner, authorised representative under Cap. 637, or investment manager - Trust: trustee - Body of persons: principal officer Enter the Name, Signature, Designation (position held), and Date (Note 6). Incorrect information may incur penalties under section 80(2D) of the Inland Revenue Ordinance.
Download the current form - always file the version on the issuing authority's site, not a copy.
Sources
More on the forms library.