Form IR1465 CbC reporting account authorization
Authorize the setup or operation of a CbC reporting account in Hong Kong by filing Form IR1465.
IR1465 at a glance
- Official title
- Authorization for Registration or Operation of a CbC Reporting Account
- Issued by
- Inland Revenue Department
We link the issuing authority's own index rather than hosting a copy, because the form is revised there and an out-of-date copy is worse than none.
Understanding Form IR1465 CbC Reporting Account Authorization
Form IR1465 authorises the registration or operation of a Country-by-Country Reporting account with the Hong Kong Inland Revenue Department. A multinational enterprise group uses this document to empower a designated person to set up and manage the CbC reporting account through the Business Tax Portal, linking the account to the group's unique group code.
What Is the CbC Reporting Account in Hong Kong?
The Country-by-Country Reporting account is a digital facility within the Inland Revenue Department's Business Tax Portal. It allows a multinational enterprise to submit CbC reports, notifications and other related filings electronically. The account is tied to the group's group code, which the IRD issues upon registration. Without an authorised account, the group cannot complete its CbC reporting obligations through the portal.
The CbC reporting regime applies to multinational enterprise groups with consolidated group revenue of HK$6.8 billion or more in the preceding fiscal year. The Hong Kong IRD requires these groups to file a CbC report and a notification of the reporting entity. The account authorisation process is the first operational step.
CbCR Account Authorization Hong Kong: Who Needs It
Any multinational enterprise group that must comply with Hong Kong's CbC reporting rules needs a CbCR account authorization Hong Kong. The authorised person is typically a director, company secretary or other senior officer of the group's Hong Kong constituent entity. The group must first obtain a group code from the IRD using Form IR1485 before it can submit Form IR1465.
The authorised person acts as the lead operator for the account. This individual is responsible for all communications and filings made through the CbC reporting account. The IRD will recognise only the authorised person's credentials when processing account-related requests.
IR1465 Application Process: Step by Step
The IR1465 application follows a defined sequence. The group must complete these steps:
-
Obtain a group code. The multinational enterprise group applies for a group code using Form IR1485. The IRD issues the code after verifying the group's details.
-
Identify the authorised person. The group designates an individual who will hold the authority to operate the CbC reporting account. This person must have a valid eTAX account or register for one through the Business Tax Portal.
-
Complete Form IR1465. The authorised person fills in the form with the group code, the group's name, the Hong Kong constituent entity's business registration number, and the authorised person's personal details.
-
Submit the form. The IRD accepts Form IR1465 through the Business Tax Portal. Paper submission is not available for this form.
-
Await confirmation. The IRD processes the application and sends a confirmation message to the authorised person's eTAX account. The account becomes active upon confirmation.
The entire IR1465 application process typically takes a few working days, though the IRD does not publish a specific processing time.
Country-by-Country Reporting Account Hong Kong: Operation and Maintenance
Once the IRD activates the Country-by-Country reporting account Hong Kong, the authorised person can use it to:
- File the annual CbC report.
- Submit the notification of the reporting entity.
- Update the group's contact details.
- Request changes to the authorised person.
The account remains active as long as the group continues to meet the CbC reporting threshold. If the group's revenue falls below the threshold, the group should notify the IRD and the account may be deactivated.
The authorised person must ensure that the account information stays current. Any change in the authorised person requires a new Form IR1465 submission. The group cannot transfer account authority without filing the form again.
Relationship Between Form IR1465 and the Group Code
The group code is a critical link in the CbC reporting process. The IRD assigns the code when the group registers using Form IR1485. Form IR1465 then connects the authorised person to that code. Without the group code, the authorised person cannot complete the account authorisation.
The group code appears on all CbC-related correspondence between the group and the IRD. The authorised person must quote the group code when making any account-related enquiry or filing.
Notification Requirements After Authorization
After the IRD activates the CbC reporting account, the group must submit a notification of the reporting entity. This notification identifies which group entity will file the CbC report. The notification is separate from the account authorisation and must be filed annually.
The authorised person uses the Business Tax Portal to submit the notification. The IRD provides a specific notification form within the portal. The group must file the notification by the deadline set out in the CbC reporting rules, typically within 12 months after the end of the reporting fiscal year.
Common Issues When Submitting Form IR1465
Several issues can delay the IR1465 application:
- Missing group code. The group must obtain the code from Form IR1485 before submitting Form IR1465.
- Incorrect business registration number. The Hong Kong constituent entity's business registration number must match the IRD's records.
- Unauthorised person. The individual named on the form must be a director, company secretary or other officer of the Hong Kong constituent entity.
- Incomplete eTAX registration. The authorised person must have an active eTAX account before the IRD can process the form.
The IRD will reject the application if any of these conditions are not met. The group must correct the issue and resubmit.
Maintaining Compliance After Account Activation
Once the CbC reporting account is active, the group must comply with ongoing obligations:
- File the CbC report annually.
- Submit the notification of the reporting entity each year.
- Update the authorised person details if the individual changes.
- Notify the IRD if the group no longer meets the revenue threshold.
The authorised person should monitor the account regularly through the Business Tax Portal. The IRD may send reminders and notices through the portal. Failure to respond can result in penalties.
Where to Find Form IR1465 and Further Guidance
The Inland Revenue Department publishes Form IR1465 on its forms index page at https://www.ird.gov.hk/eng/paf/bus.htm. The form is available for download in PDF format. The IRD also provides guidance notes that explain the completion requirements in detail.
The Business Tax Portal is accessible at https://www.ird.gov.hk/eng/tax/bus_epf.htm. The authorised person logs in using their eTAX credentials to submit the form and manage the account.
For groups that need assistance, the IRD operates a helpline for CbC reporting enquiries. The contact details are available on the IRD website.
How to fill out Form IR1465
Page one of the official form. Every field named below appears on it in the same order.
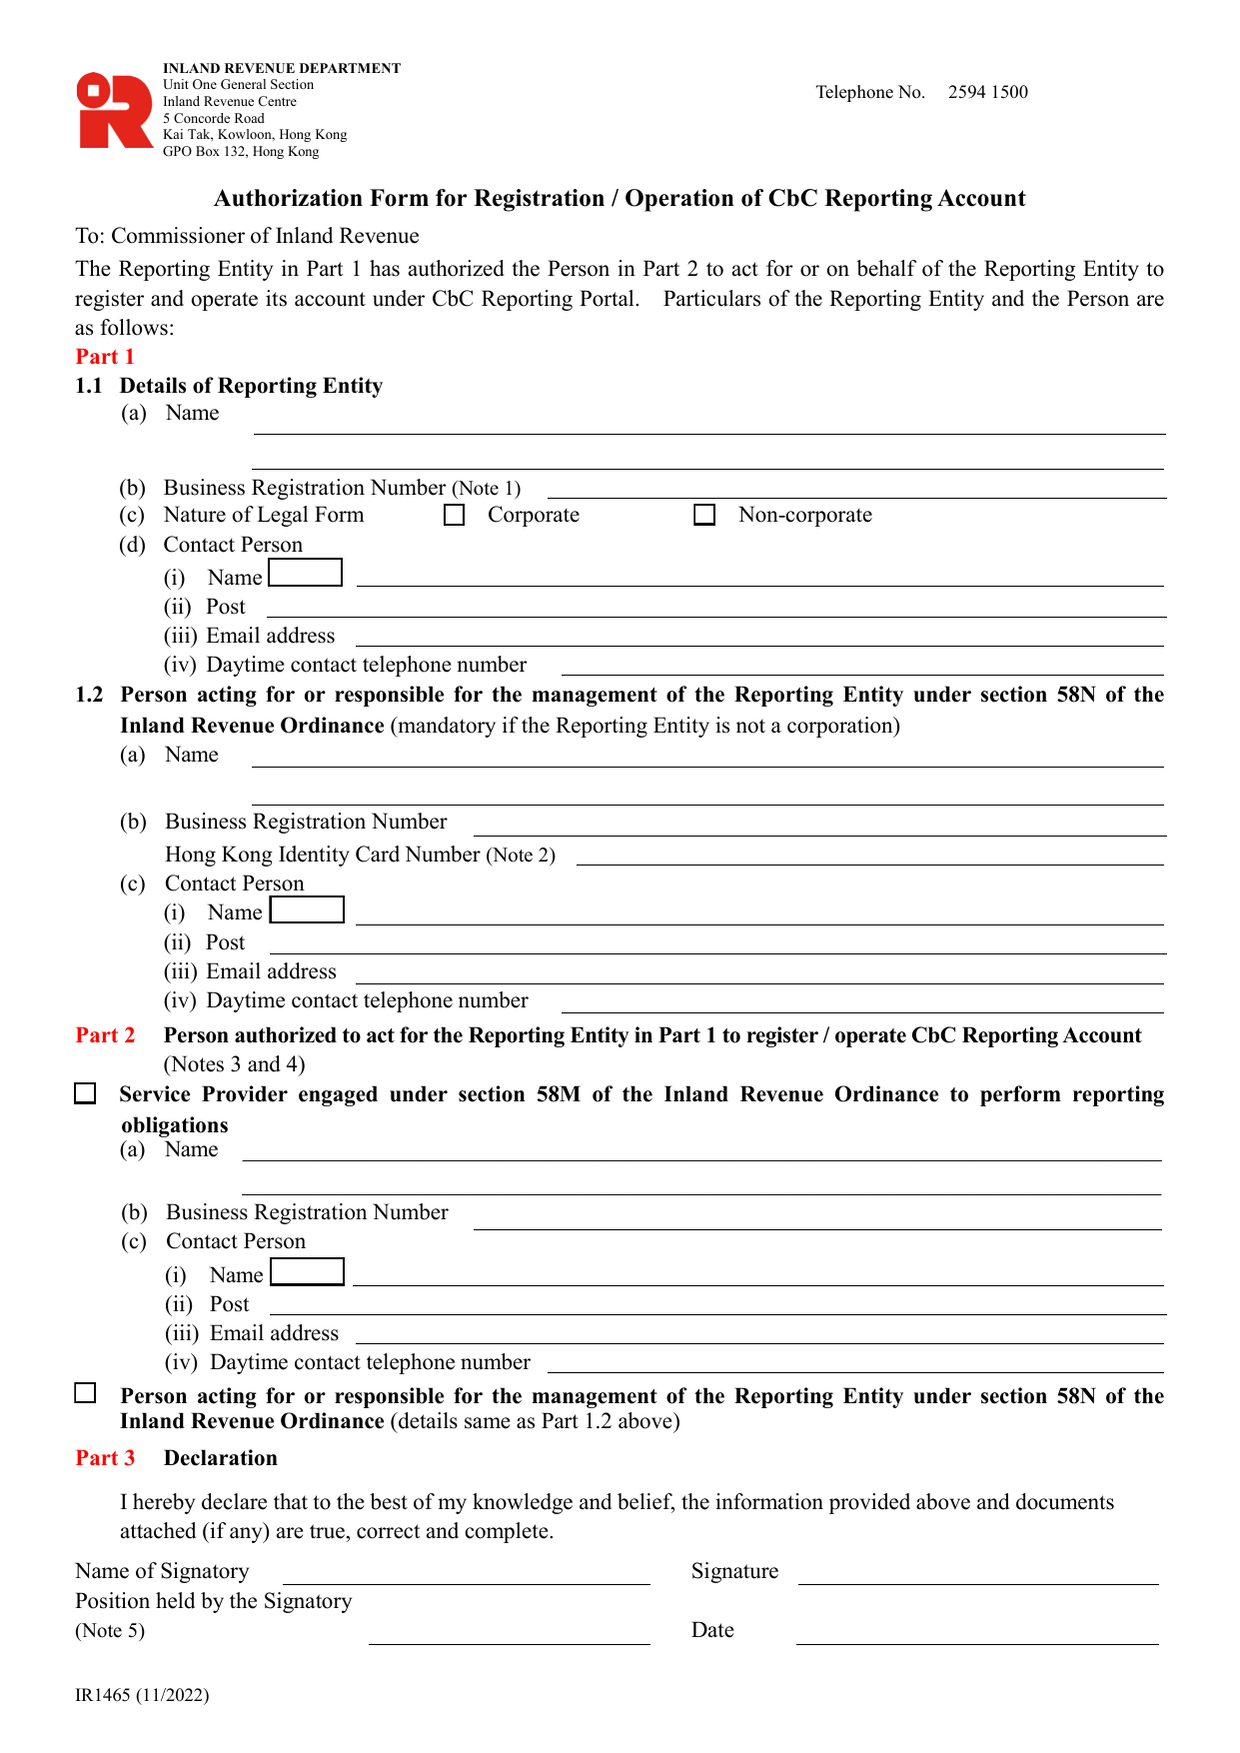
Part 1 - Details of Reporting Entity
1.1 (a) Name
Enter the full legal name of the Reporting Entity as it appears on its Certificate of Incorporation or Business Registration Certificate.
1.1 (b) Business Registration Number
Enter the Business Registration (BR) number from the entity’s BR certificate. If the entity does not carry on business in Hong Kong and has no BR number, you must first write to the Department to apply for a BR Number Equivalent before submitting this form (Note 1).
1.1 (c) Nature of Legal Form
Tick either Corporate or Non-corporate. This determines who must sign in Part 3 (see Note 5).
1.1 (d) Contact Person
Provide the name, post, email address and daytime contact telephone number of a person the Department can contact about this authorization.
1.2 Person acting for or responsible for the management of the Reporting Entity under section 58N of the Inland Revenue Ordinance
Complete this section only if the Reporting Entity is not a corporation.
- (a) Name - Full name of the individual.
- (b) Business Registration Number - If the individual carries on business in Hong Kong, enter their BR number. If they do not, they must first apply for a BR Number Equivalent (Note 2).
- Hong Kong Identity Card Number - Required if the person is an individual (Note 2).
- (c) Contact Person - Name, post, email and daytime telephone number for this individual.
Part 2 - Person Authorized to Act for the Reporting Entity
Tick one of the two mutually exclusive boxes:
- Service Provider engaged under section 58M - Complete fields (a) Name, (b) Business Registration Number, and (c) Contact Person (name, post, email, daytime telephone).
- Person acting for or responsible for the management of the Reporting Entity under section 58N - If ticked, the details are the same as those already provided in Part 1.2. Do not repeat them.
Important: Only the Person in Part 2 who holds a specified digital certificate (e-Cert (Organisational) with AEOI Functions) will be allowed to open and operate the CbC Reporting Account online (Note 3). If the Person in Part 2 ceases to be authorized, the Reporting Entity’s account profile must be updated immediately (Note 4).
Part 3 - Declaration
Name of Signatory - Print the full name of the individual signing.
Signature - The signatory must sign manually.
Position held by the Signatory - Must match one of the categories in Note 5:
- Director or officer (if corporation)
- Partner (if partnership)
- Trustee (or director/officer of corporate trustee) (if trust)
- Principal officer or responsible person (if body of persons)
Date - Enter the date of signing.
Common mistakes:
- Forgetting to apply for a BR Number Equivalent before submitting the form if the entity or individual does not have a Hong Kong BR number.
- Leaving Part 1.2 blank when the entity is non-corporate.
- Signing by a person not listed in Note 5.
Download the current form - always file the version on the issuing authority's site, not a copy.
Sources
More on the forms library.