Form IR6167 Notification of Chargeability to Salaries Tax
Notify the Hong Kong IRD of your chargeability to salaries tax by completing Form IR6167 when you start a new job.
IR6167 at a glance
- Official title
- Notification of Chargeability to Salaries Tax
- Issued by
- Inland Revenue Department
We link the issuing authority's own index rather than hosting a copy, because the form is revised there and an out-of-date copy is worse than none.
Form IR6167 Notification of Chargeability to Salaries Tax
Form IR6167 notifies the Inland Revenue Department that an individual is now liable for Hong Kong salaries tax. This liability arises when a person starts employment in Hong Kong or derives other income from a Hong Kong source chargeable to salaries tax. This form is not a tax return. It is a preliminary notification that prompts the department to issue the individual's first Individual Tax Return, Form BIR60.
When to File the Notification of Chargeability
You must notify the Inland Revenue Department when you first become a chargeable person. This happens when you commence employment in Hong Kong. Your duty to notify is separate from your employer's obligations, which are fulfilled by filing Form IR56B or Form IR56E. The employer's reporting does not absolve you of this personal responsibility.
File as soon as you have reasonable grounds to believe you will be chargeable for a year of assessment. If you arrive in Hong Kong to take up a job and expect to earn income from a local source, file Form IR6167 promptly. Delaying your notification can lead to a late-filing notice or penalties from the Inland Revenue Department.
Salaries Tax Notification Hong Kong
The process begins when you realise your income from employment, office, or pension is subject to Hong Kong salaries tax. The department will not know this automatically. You must self-declare your liability using Form IR6167.
The form requires basic personal information: your name, Hong Kong Identity Card number, correspondence address, and contact details. You must also provide the date your employment commenced and your employer's name and address. The department uses this information to create your tax file and issue the first tax return at the appropriate time.
Form IR6167 for New Employee
Provide accurate details about your employment start date and expected income on Form IR6167. The Inland Revenue Department uses this to determine the correct assessment year. You do not calculate your tax liability on this form; you simply notify the department of your chargeability.
Even if your employer has filed Form IR56E, you must still file Form IR6167 if you have never filed a tax return in Hong Kong. The employer's notification is for their records and does not remove your personal obligation. While the department may issue your first tax return based on the employer's filing, your own notification ensures your personal details and correspondence address are correct.
Starting Employment Tax HK
Starting employment involves three key steps. First, your employer notifies the Inland Revenue Department of your hiring using Form IR56E within three months of your start date. Second, you file Form IR6167 to notify the department of your own chargeability. Third, the department issues your first Individual Tax Return, Form BIR60, for the relevant year of assessment.
Hong Kong's year of assessment runs from 1 April to 31 March. If you start work on 1 September 2025, you are chargeable for the 2025-26 year of assessment. The department will issue Form BIR60 for that year after receiving your notification. You must then file that return by its deadline, typically within one month of the issue date.
Chargeability to Salaries Tax Form
Form IR6167 is available for download from the Inland Revenue Department's website. You can complete it manually or electronically. Submit the completed form by post or through the eTAX portal if you are registered.
The form is straightforward. You must declare your full name, Hong Kong Identity Card number, date of birth, correspondence address, and contact telephone number. You also provide your Hong Kong employment commencement date and your employer's name and address. If you are self-employed or have income from another source, indicate the nature of that income.
IR6167 Filing Guide
The Inland Revenue Department's filing guide explains how to complete and submit the form. It advises filing as soon as you become chargeable to salaries tax and clarifies that the form is not a tax return, so no tax calculation is required.
Keep a copy of the completed form for your records. The department will acknowledge receipt by issuing a tax file number or updating its records. Expect to receive your first tax return within a few months of filing, depending on the assessment year's timing.
Relationship with Other Forms
Form IR6167 is one of several forms the Inland Revenue Department uses for salaries tax. Form BIR60 is the annual Individual Tax Return you must file. Employers use Form IR56B to report annual remuneration and Form IR56E to notify the department of a new employee within three months of their start date.
If you have already received a tax return for a previous year, you do not need to file Form IR6167 again. It is only for first-time notification. Once the department has issued a tax return, you must file Form BIR60 annually until you are no longer chargeable to salaries tax.
Provisional Salaries Tax and the First Tax Return
After receiving Form IR6167, the department will issue your first tax return. This return covers the year of assessment in which you became chargeable. It will also include a provisional salaries tax computation for the following year. You must file the return and pay any tax due by the specified deadline.
If your estimated income for the following year is lower than the amount used for the provisional tax, you can apply to holdover the provisional tax. Use Form IR1121 for this application. The department will consider your request and may grant a holdover if you meet the criteria.
Obligation to Notify and Penalties
Notifying the Inland Revenue Department of your chargeability is a legal requirement under the Inland Revenue Ordinance (Cap. 112). Failure to notify within a reasonable time can result in a penalty of up to three times the amount of tax that would have been assessed had you notified on time.
The department may also impose a late-filing penalty if you fail to file your tax return by the due date. The penalty for late filing of Form BIR60 is HK$1,200 for the first offence and HK$3,000 for subsequent offences. The department may also prosecute individuals who deliberately fail to notify their chargeability.
Where to Obtain Form IR6167
Download Form IR6167 from the Inland Revenue Department's forms index at https://www.ird.gov.hk/eng/paf/bus.htm. The form is also available at the department's offices. If you are registered for eTAX, you can submit the form electronically through the portal, which the department recommends for faster processing.
The department's website also contains guidance notes for completing Form IR6167. These notes explain the legal basis for the notification and provide examples of when you must file. If you are unsure whether you need to file, consult the guidance notes or contact the Inland Revenue Department for clarification.
How to fill out Form IR6167
Page one of the official form. Every field named below appears on it in the same order.
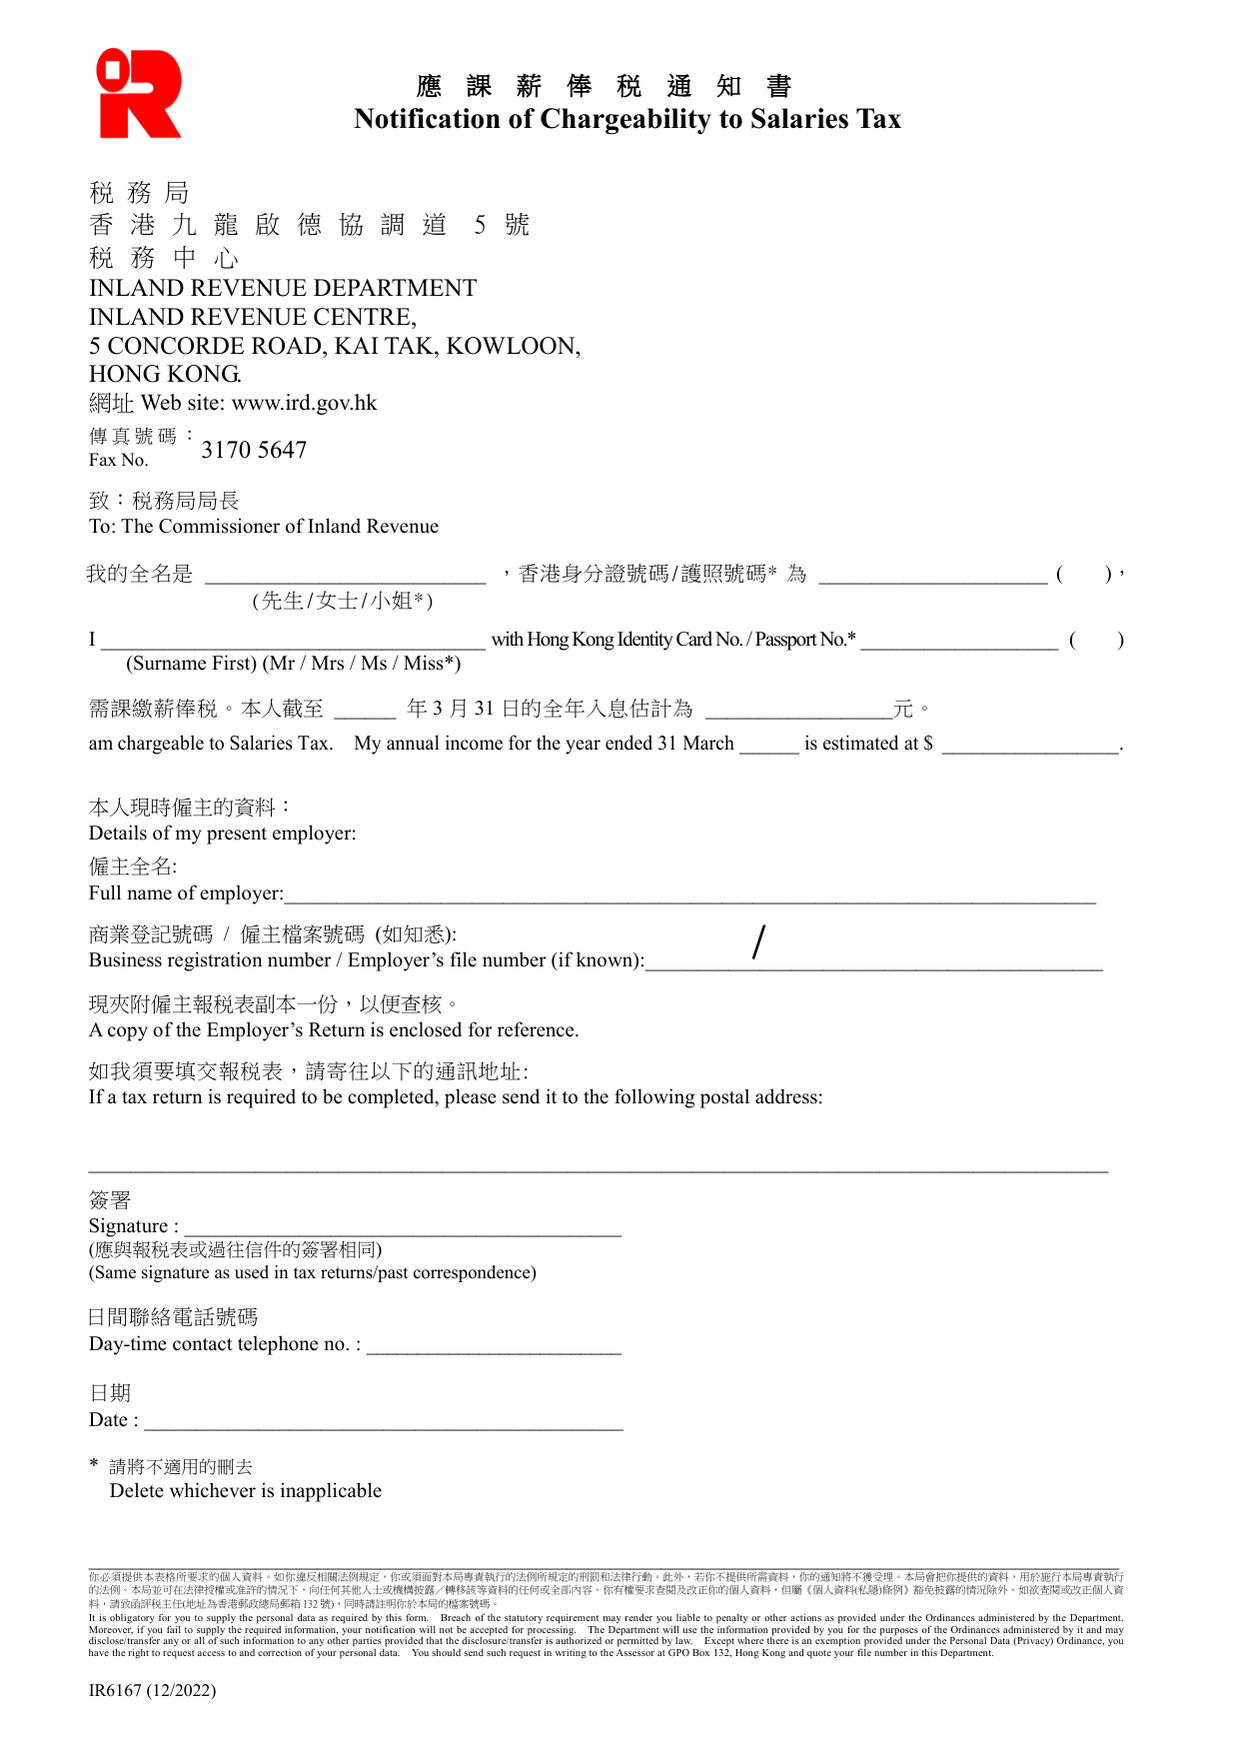
我的全名是 / I … with Hong Kong Identity Card No. / Passport No.
Enter your full name in English (surname first, then given name) as it appears on your Hong Kong Identity Card or passport. Tick the appropriate title (Mr / Mrs / Ms / Miss). In the next box, enter your Hong Kong Identity Card number or passport number. The brackets after the number are for the check digit (the digit printed after the number on your ID card); include it.
需課繳薪俸税 / am chargeable to Salaries Tax
Enter the year ended 31 March (for example, 2025 for the year ending 31 March 2025). Then enter your estimated total annual income for that year in Hong Kong dollars. This is your own estimate; you do not need to have received an Employer’s Return yet.
本人現時僱主的資料 / Details of my present employer
Provide the full name of your current employer exactly as it appears on your payslip or employment contract. In the next box, enter the employer’s Business Registration number or Employer’s file number if you know it. The business registration number is on the employer’s Business Registration certificate; the employer’s file number is the number the IRD uses for that employer. If you do not know either, leave the box blank.
現夾附僱主報税表副本一份 / A copy of the Employer’s Return is enclosed
Tick this box only if you are actually enclosing a copy of your employer’s return (the form your employer filed with the IRD about your pay). If you do not have it, do not tick the box.
如我須要填交報税表,請寄往以下的通訊地址 / If a tax return is required, please send it to the following postal address
Write your postal address where you want the IRD to send a tax return if one is needed. This can be your home address or a correspondence address. Do not leave it blank.
簽署 / Signature
Sign exactly as you have signed previous tax returns or correspondence with the IRD. The form warns that the signature should match. Unsigned notifications will not be processed.
日間聯絡電話號碼 / Day-time contact telephone no.
Provide a telephone number where you can be reached during business hours.
日期 / Date
Enter the date you sign the form.
注意事項
- Delete whichever is inapplicable: cross out “先生/女士/小姐” and “護照號碼” if they do not apply.
- The form is a notification, not a tax return. It tells the IRD you believe you are chargeable to salaries tax. No fee is stated on this form.
- If you do not supply the required personal data, your notification will not be accepted for processing.
Download the current form - always file the version on the issuing authority's site, not a copy.
Sources
More on the forms library.