Form IR6168 Notification of Chargeability to Profits Tax
File Form IR6168 to notify the Inland Revenue Department when your business becomes chargeable to Hong Kong profits tax.
IR6168 at a glance
- Official title
- Notification of Chargeability to Profits Tax
- Issued by
- Inland Revenue Department
We link the issuing authority's own index rather than hosting a copy, because the form is revised there and an out-of-date copy is worse than none.
Form IR6168 Notification of Chargeability to Profits Tax
Starting a trade, profession or business in Hong Kong triggers a legal duty to notify the Inland Revenue Department (IRD) of your chargeability to profits tax. The Form IR6168 notification of chargeability to profits tax is the official document for this purpose. Below is the obligation, the submission deadline and the filing process.
Starting Business Profits Tax Hong Kong
The obligation to notify the IRD arises the moment a person starts a business in Hong Kong. A "person" can be an individual, a partnership, a corporation, a club or an association. The trigger is the commencement of a trade, profession or business carried on in Hong Kong that generates or is expected to generate assessable profits.
The IRD does not automatically know when a new business begins. The onus is on the chargeable person to come forward. Failure to notify can result in penalties, including a fine of up to HK$10,000 and a further penalty equal to three times the amount of tax undercharged.
Form IR6168 Filing Requirement
Form IR6168 is the standard notification form issued by the IRD. It requires the name and business registration number, the date of commencement, the nature of the business activity, the business and correspondence addresses, the name and address of any tax representative, and the accounting period end date.
A proprietor must sign for a sole proprietorship, all partners for a partnership, or a director or company secretary for a corporation. Use the current version from the IRD website, as the department revises forms periodically.
New Business Tax Notification HK
The notification must be given within four months after the end of the basis period for the first year of assessment in which the business is chargeable to profits tax.
For example, a sole trader starts business on 1 June 2025 and intends to make up accounts to 31 March each year. The first basis period runs from 1 June 2025 to 31 March 2026. The notification must reach the IRD by 31 July 2026.
If the business makes up accounts to 31 December, the first basis period runs from 1 June 2025 to 31 December 2025. The notification must reach the IRD by 30 April 2026. The deadline is strict. Late notification may attract penalties.
Profits Tax Commencement Notification
This notification is separate from business registration. A person holding a valid business registration certificate under the Business Registration Ordinance (Cap. 310) must still file Form IR6168 if they are chargeable to profits tax.
The IRD cross-references business registration data with profits tax records, but it expects the taxpayer to take the active step of filing. Relying on the IRD to issue a profits tax return without notification is not a defence.
After receiving the notification, the IRD may issue a profits tax return (BIR51 for corporations or BIR52 for persons other than corporations). This return will cover the first year of assessment and subsequent years until the IRD issues returns on a regular cycle.
IR6168 Guide
The IRD provides a guide to completing Form IR6168. It explains who must file, when to file, where to send the form, and what to attach.
Any person chargeable to profits tax who has not yet received a profits tax return from the IRD must file. The filing deadline is within four months after the end of the first basis period. Send the completed form to the Inland Revenue Department, at the address shown on the form.
If the business has already prepared accounts for the first period, attach the accounts and tax computation. If accounts are not yet ready, the form alone is sufficient; the accounts will be requested later. A person who has already received a profits tax return (BIR51 or BIR52) should not file Form IR6168. They should complete and file the return by the due date stated on it.
Filing Channels
Form IR6168 can be filed by post or in person at the IRD's office. The IRD does not currently accept electronic filing of Form IR6168 through the Business Tax Portal.
Once the IRD issues a profits tax return, that return must be filed through the Business Tax Portal or the Tax Representative Portal, as applicable. A taxpayer must register for an eTAX account to use the portal.
Tax Representative
A taxpayer may appoint a tax representative, such as a certified public accountant or a tax adviser, to handle communications with the IRD. Make the appointment by completing the relevant section on Form IR6168 or by filing a separate letter of authorisation.
If a representative is appointed, the IRD will send all correspondence, including the first profits tax return, to them. The taxpayer remains ultimately responsible for meeting all filing obligations.
Provisional Tax
After the first profits tax return is assessed, the IRD will issue a notice of assessment and demand for payment. This assessment will include provisional tax for the following year of assessment. Provisional tax is an advance payment of the estimated tax for the next year.
A taxpayer who expects their profits to be lower than the amount on which provisional tax is based may apply to holdover the provisional tax using Form IR1121. Make the application within the time limit stated in the notice of assessment.
Obligation to Notify
The obligation to notify the IRD of chargeability to profits tax is set out in the Inland Revenue Ordinance (Cap. 112). Section 51(2) of the Ordinance requires every person chargeable to tax to give notice of chargeability within four months after the end of the basis period for the year of assessment.
This obligation applies even if the person has not yet received a tax return. It also applies if the person expects to make a loss in the first period. A person who makes a loss is still chargeable to tax in the sense that they are within the charge to tax, even if no tax is payable.
The IRD may issue a notice under section 51(1) requiring a person to file a return. However, the obligation under section 51(2) is self-executing. The taxpayer must act without waiting for a notice.
Penalties for Non-Compliance
Failure to notify the IRD of chargeability is an offence under the Inland Revenue Ordinance. The maximum penalty on conviction is a fine of HK$10,000 and a further penalty equal to three times the amount of tax undercharged.
The IRD may also raise an estimated assessment under section 59(3) if it believes a person is chargeable to tax but has not filed a return. An estimated assessment is based on the IRD's best estimate of the person's profits and may be higher than the actual profits. The taxpayer must then object to the assessment and provide evidence of the correct profits.
Practical Steps
A person starting a business in Hong Kong should take the following steps:
- Register the business with the within one month of commencement.
- Obtain a business registration certificate.
- Determine the accounting period end date.
- Complete Form IR6168 and send it to the IRD within four months after the end of the first basis period.
- Keep records of all income and expenses from the start of the business.
- Prepare accounts and a tax computation for the first period.
- File the first profits tax return (BIR51 or BIR52) when the IRD issues it.
The IRD's website provides the current version of Form IR6168 and the accompanying guide. Download the form from the IRD's forms index; the department revises forms periodically.
How to fill out Form IR6168
Page one of the official form. Every field named below appears on it in the same order.
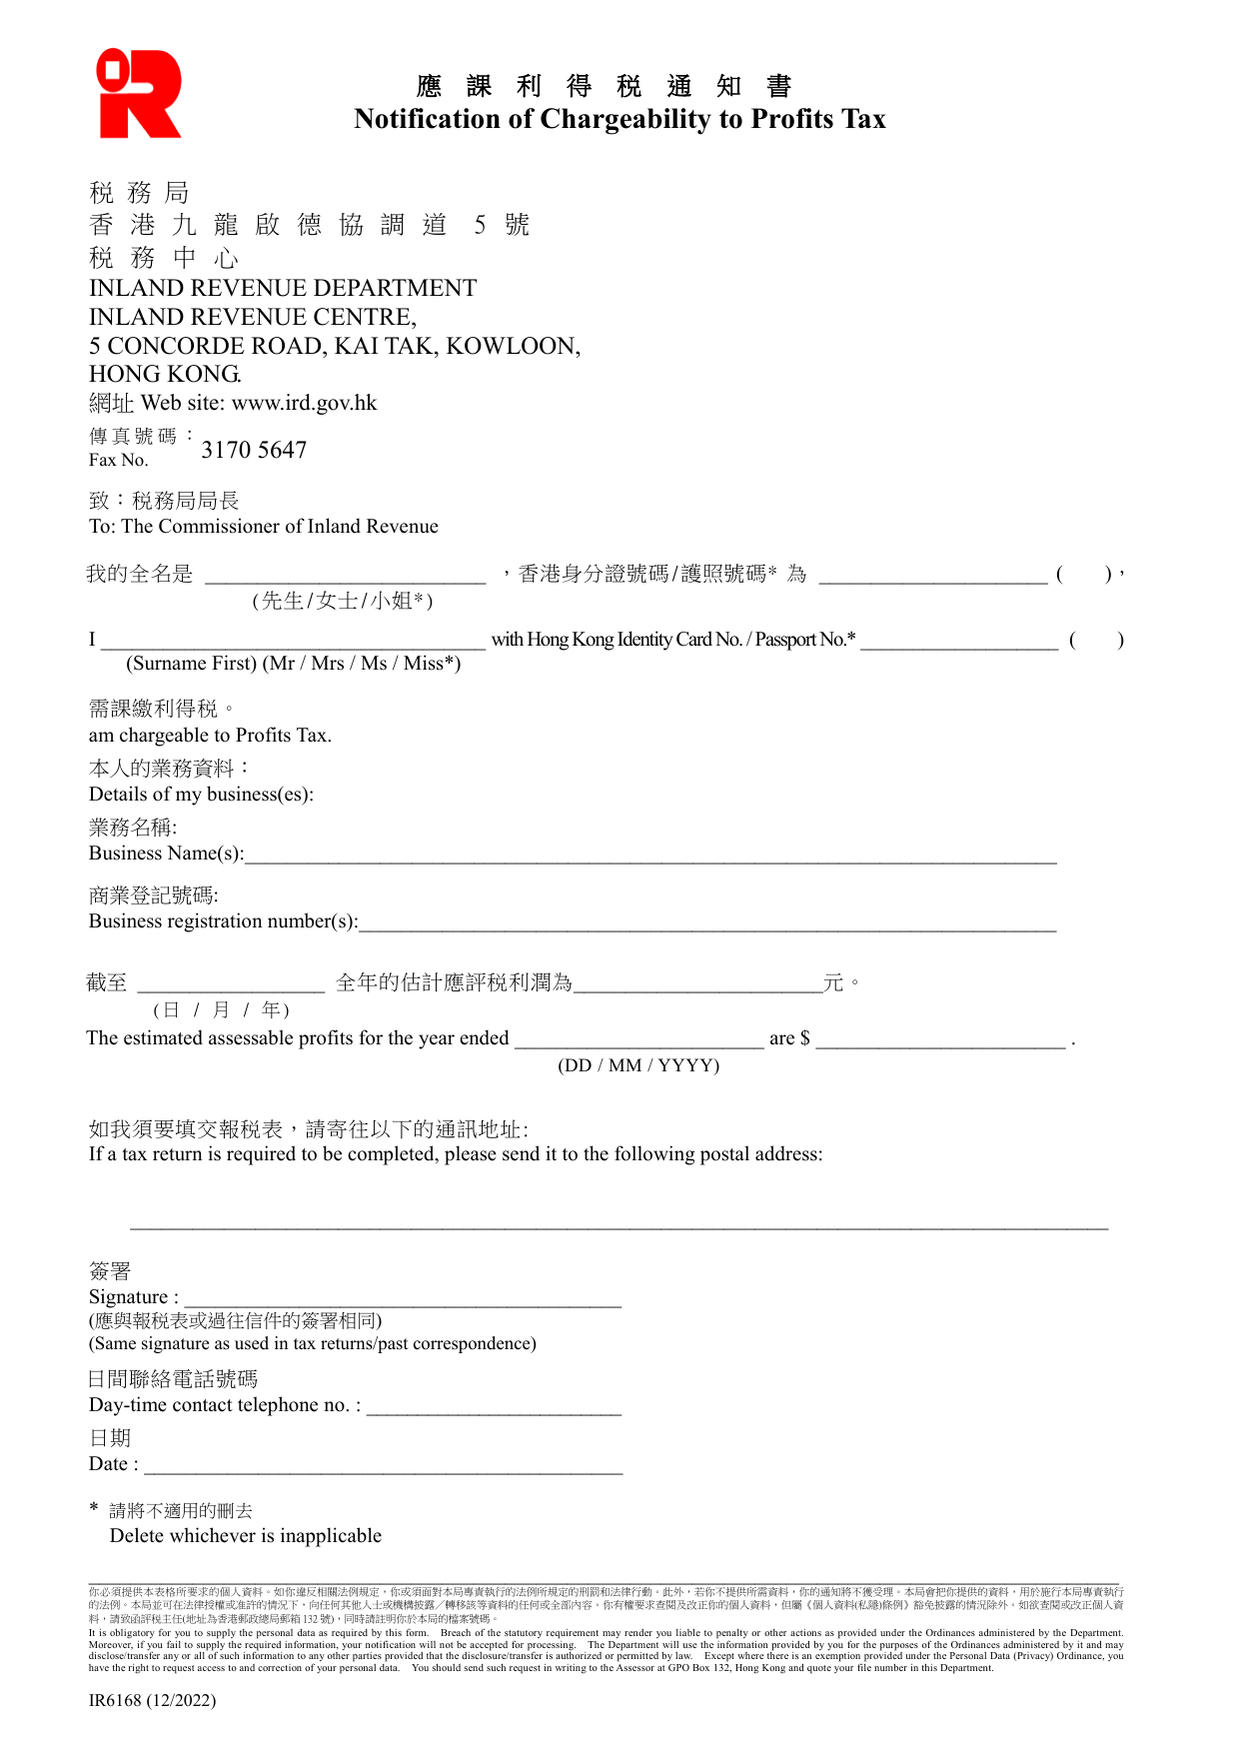
我的全名是 / I _______ with Hong Kong Identity Card No. / Passport No.* _______ ( )
Enter your full name in English, surname first. In the second box, enter your Hong Kong Identity Card number or passport number. Cross out the title (Mr / Mrs / Ms / Miss) that does not apply. The form is signed by an individual, not a company.
需課繳利得税 / am chargeable to Profits Tax
This is a declaration. By signing the form you confirm that you are chargeable to Profits Tax for the year. No separate entry is required here.
本人的業務資料 / Details of my business(es)
業務名稱 / Business Name(s): Enter the name of each business you operate. If you have more than one business, list all names. Use a continuation sheet if the space is insufficient.
商業登記號碼 / Business registration number(s): Enter the Business Registration number for each business. This number is on the Business Registration Certificate issued by the Inland Revenue Department. If you have multiple businesses, list each number next to the corresponding business name.
截至 ___ 全年的估計應評税利潤為 ___元 / The estimated assessable profits for the year ended ___ are $ ___
Enter the date of the accounting year end in DD/MM/YYYY format. This date must match the year end of your business accounts. In the second box, enter your estimated assessable profits for that full year. This is your best estimate of the profit that will be subject to Profits Tax. If you expect a loss, enter "0" or state "Loss". Do not leave this blank.
如我須要填交報税表,請寄往以下的通訊地址 / If a tax return is required to be completed, please send it to the following postal address
Enter your postal address where you want the tax return to be sent. This address is used only if the Department decides to issue a return. If you already have a correspondence address on file, you may still provide a different address here.
簽署 / Signature
Sign exactly as you sign tax returns or past correspondence with the Inland Revenue Department. The signature must match the name you entered at the top of the form. Do not use a stamp or typed name.
日間聯絡電話號碼 / Day-time contact telephone no.
Enter a telephone number where you can be reached during business hours. Include the area code if applicable.
日期 / Date
Enter the date you sign the form in DD/MM/YYYY format. This date should be the same as the date of signing.
請將不適用的刪去 / Delete whichever is inapplicable
Cross out the options that do not apply to you in the top section (Hong Kong Identity Card No. / Passport No. and Mr / Mrs / Ms / Miss). If you use a passport, delete the Identity Card option. If you are a woman, delete the titles that do not match your status.
Download the current form - always file the version on the issuing authority's site, not a copy.
Sources
More on the forms library.