Form IR623 notification of non-resident entertainers
Understand Form IR623 requirements for notifying the IRD of non-resident entertainers and sportsmen performing in Hong Kong.
IR623 at a glance
- Official title
- Notification of Arrival of Non-resident Entertainers or Sportsmen
- Issued by
- Inland Revenue Department
We link the issuing authority's own index rather than hosting a copy, because the form is revised there and an out-of-date copy is worse than none.
Form IR623 Notification of Non-Resident Entertainers
When a non-resident entertainer or sportsman performs in Hong Kong, the person who pays them must notify the Inland Revenue Department (IRD). The Form IR623 notification of non-resident entertainers is the prescribed form for this purpose. This notification lets the IRD assess whether withholding tax should be deducted from the performance income before the payment reaches the non-resident.
Hong Kong taxes income that arises in or is derived from Hong Kong. Payments for performances that take place in Hong Kong are Hong Kong source income. The IRD uses the information on Form IR623 to determine the tax obligation of the non-resident entertainer and to collect any tax due, often by requiring the payer to withhold a percentage of the payment.
Who Must File Form IR623
The obligation to file rests on the "prescribed person". This is anyone who pays, or is liable to pay, any sum to a non-resident entertainer or sportsman for a performance in Hong Kong. The prescribed person can be a promoter, producer, agent or manager who arranges the performance, a venue owner or operator, a sponsor who makes a payment directly to the non-resident, or any other person who has the contractual obligation to pay.
If there is more than one prescribed person, the IRD expects the person who controls the payment to file. Where no single person controls the payment, all prescribed persons are jointly and severally liable for the tax, and each should ensure that a notification is made.
Non-Resident Entertainer Tax Hong Kong
The term "non-resident entertainer" is defined broadly under section 15 of the Inland Revenue Ordinance (Cap. 112). It covers actors, musicians, singers, dancers and other performers, sportsmen and athletes, and persons who appear as entertainers or sportsmen in any public event, film, television programme or advertisement.
A person is non-resident if they are not ordinarily resident in Hong Kong and do not carry on a trade, profession or business in Hong Kong through a permanent establishment. The rule catches both individuals and companies that provide entertainment services.
The tax base is the gross performance income, not the net profit. The IRD does not allow deductions for travel, accommodation, agent fees or other expenses when calculating the tax due from the non-resident entertainer. The withholding tax rate is applied to the full amount of the payment.
Ir623 Filing Obligations
The filing obligation arises before the performance takes place. Form IR623 must be submitted to the IRD no later than the day the non-resident arrives in Hong Kong to perform, or as soon as reasonably practicable after the contract is signed, whichever is earlier.
The form requires the following particulars of performance: name, address and tax reference number of the prescribed person; name and address of the non-resident entertainer or sportsman; country of residence of the non-resident; date and venue of the performance; nature of the performance (e.g. concert, sporting event, film shoot); contract amount or fee payable; any amounts already paid or advanced; and the name of any agent or representative in Hong Kong.
The IRD uses this information to issue a notice of assessment or to confirm that no withholding tax is required. Until the IRD responds, the prescribed person should retain the payment and not release it to the non-resident.
Withholding Tax Entertainers Hong Kong
Under section 20B of the Inland Revenue Ordinance (Cap. 112), the prescribed person who pays a non-resident entertainer must deduct tax from the payment at the applicable rate. The standard rate is the profits tax rate for corporations or the standard rate for individuals, applied to the gross payment. As of the current year of assessment, the profits tax rate for corporations is 16.5% and the standard rate for individuals is 15%.
The prescribed person must pay the withheld amount to the IRD within 14 days after the payment is made. If the prescribed person fails to withhold, the IRD may assess them directly for the tax due. The IRD can also impose a penalty of up to 100% of the tax underpaid.
If the IRD determines that no tax is payable, it will issue a notice to that effect. The prescribed person can then release the full payment to the non-resident without deduction.
What Information Must Be Provided on Form IR623
Form IR623 asks for the following details in a structured format:
- Part A: Particulars of the prescribed person (name, address, business registration number, telephone number)
- Part B: Particulars of the non-resident entertainer (name, address, country of residence, passport number if available)
- Part C: Particulars of the performance (date, venue, type of entertainment, duration)
- Part D: Contract particulars (total fee payable, currency, payment schedule, amounts already paid)
- Part E: Declaration signed by the prescribed person confirming the information is correct
The IRD recommends attaching a copy of the contract or engagement letter, though this is not mandatory. If the contract is in a language other than English or Chinese, a translation should be provided.
Submission Deadline and Penalties for Late Filing
The submission deadline for Form IR623 is strict. The prescribed person must file the form before the non-resident arrives in Hong Kong or within a reasonable time after the contract is signed. In practice, the IRD expects the form to be filed at least seven days before the performance date.
Late filing can result in a penalty of up to HK$10,000 under section 80 of the Inland Revenue Ordinance. The IRD may also issue a default assessment for the tax due, which the prescribed person must pay even if they have not yet collected the payment from the non-resident. The prescribed person becomes personally liable for any tax that remains unpaid.
If the prescribed person discovers that they have missed the deadline, they should file Form IR623 immediately and explain the delay in the covering letter. The IRD may mitigate the penalty if the late filing was due to reasonable cause.
How to File Form IR623
Form IR623 can be filed by post or in person at the Inland Revenue Department's Profits Tax Section. The address is:
Inland Revenue Department
Inland Revenue Centre
5 Concorde Road
Kai Tak, Kowloon
Hong Kong
The form is available for download from the IRD website at www.ird.gov.hk. The IRD does not currently accept electronic filing of Form IR623, but the prescribed person can send it by fax or email with a scanned signature.
The prescribed person should keep a copy of the filed form and any correspondence with the IRD. If the IRD does not respond within 14 days, the prescribed person should follow up by telephone or in writing.
Practical Considerations for Prescribed Persons
When arranging a performance by a non-resident entertainer, the prescribed person should confirm the residency status of the entertainer before signing the contract. Include a clause in the contract that allows the payer to deduct withholding tax if required. File Form IR623 as early as possible to avoid last-minute complications. Do not release any payment to the non-resident until the IRD has confirmed the tax position. Keep records of all payments and correspondence for at least seven years.
If the non-resident entertainer has a Hong Kong agent, the agent may assist with the notification, but the legal obligation remains with the prescribed person who makes the payment.
Relationship with Double Taxation Agreements
Hong Kong has comprehensive double taxation agreements with many jurisdictions. Some of these agreements reduce or exempt the withholding tax on payments to non-resident entertainers. However, the exemption is not automatic. The prescribed person must still file Form IR623 and provide evidence that the entertainer qualifies for the reduced rate or exemption.
The IRD may require a Certificate of Resident Status from the entertainer's home tax authority to confirm treaty eligibility. The prescribed person should request this document well in advance of the performance.
Summary of Key Points
Form IR623 must be filed before the non-resident entertainer arrives in Hong Kong. The prescribed person who pays the entertainer is responsible for filing. Failure to file or to withhold tax can result in personal liability for the prescribed person. The tax is calculated on the gross payment, not the net amount after deductions. Double taxation agreements may reduce the rate, but the notification obligation remains.
How to fill out Form IR623
Page one of the official form. Every field named below appears on it in the same order.
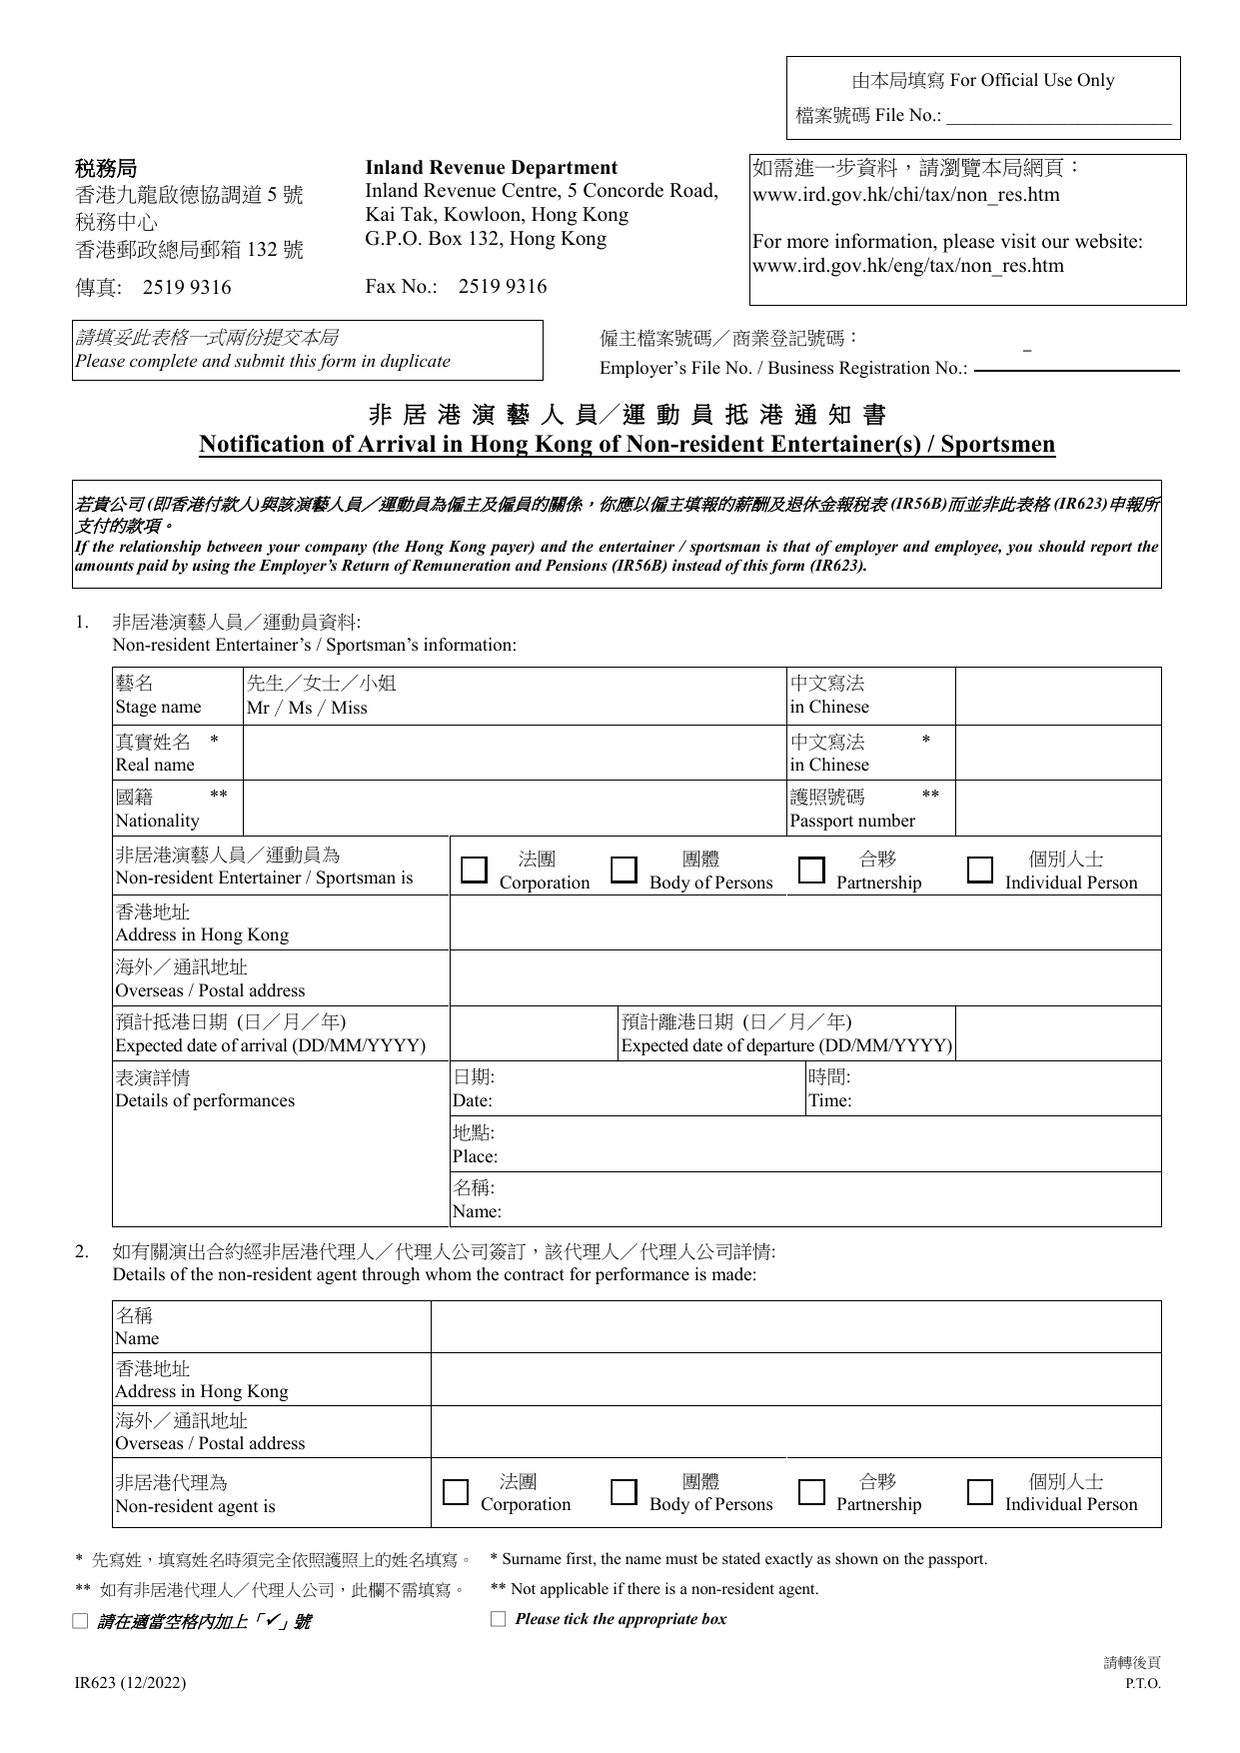
1. 非居港演藝人員/運動員資料 (Non-resident Entertainer’s / Sportsman’s information)
- 藝名 / Stage name and 真實姓名 / Real name: Enter the stage name and real name. For real name, write surname first and exactly as shown on the passport.
- 國籍 / Nationality and 護照號碼 / Passport number: Leave blank if a non-resident agent is involved (see section 2).
- 非居港演藝人員/運動員為 / Non-resident Entertainer / Sportsman is: Tick one box: Corporation, Body of Persons, Partnership, or Individual Person.
- 香港地址 / Address in Hong Kong: Provide a local address during the stay.
- 海外/通訊地址 / Overseas / Postal address: Provide the overseas or permanent mailing address.
- 預計抵港日期 / Expected date of arrival and 預計離港日期 / Expected date of departure: Use DD/MM/YYYY format.
- 表演詳情 / Details of performances: Enter the Date, Time, Place, and Name of each performance.
2. 非居港代理人/代理人公司詳情 (Details of the non-resident agent)
Fill this section only if the performance contract was made through a non-resident agent.
- 名稱 / Name: Full name of the agent or agency.
- 香港地址 / Address in Hong Kong: Local address.
- 海外/通訊地址 / Overseas / Postal address: Permanent or mailing address.
- 非居港代理為 / Non-resident agent is: Tick one box: Corporation, Body of Persons, Partnership, or Individual Person.
Note: When an agent is listed, the entertainer’s nationality and passport number in section 1 are not required.
3. 香港付款人的資料 (Hong Kong payer’s information)
- 公司名稱 / Name of company: Your company name.
- 商業登記號碼 / Business registration number: Your BR number (on the BR certificate). Write this also in the 僱主檔案號碼/商業登記號碼 field at the top of the form, which appears before section 1.
- 電話號碼 / Telephone number: Contact phone.
- 通訊地址 / Postal address: Your postal address.
4. 合約副本 (Copy of contract)
Tick 是 / Yes if you attach a copy of the contract with the entertainer. Write your Employer’s File No. or BR number on that copy. If 否 / No, explain the reason in the space provided.
5. 是否已付或將付給演藝人員/運動員款項 (Payment to entertainer/sportsman)
Tick 是 / Yes and fill in section 6, or tick 否 / No and give reasons.
6. 列明已付或將付給演藝人員/運動員款項 (Details of payments)
For each payment: 付款日期 / Date of Payment, 包括的期間 / Period covered, 應付款項 / Gross amount payable, 減 : 預扣税款 / Less: Amount deducted for tax payment, and 付款淨值 / Net amount paid or payable.
7. 兩級制利得税率課税 (Two-tiered profits tax rates)
Tick 是 / Yes or 否 / No. If yes, you must also file a relevant tax return to make the declaration.
8. 税款是否由香港付款人負擔 (Tax borne by Hong Kong payer)
Tick 是 / Yes or 否 / No.
9. 款項是付予另一香港人士 (Payment to another person in Hong Kong)
If applicable, provide 姓名 / Name, 通訊地址 / Postal address, and 電話號碼 / Telephone number.
10. 演藝人員之前曾透過你的安排在香港表演 (Previous File No.)
If the entertainer has performed through your arrangement before, state the previous IRD 檔案號碼 / File No..
簽署 (Signature)
- 簽署 / Signature: Authorised signatory.
- 職位 / Designation: Signatory’s job title.
- 電話 / Telephone number: Contact number.
- 日期 / Date: Date of signing.
- (公司蓋印 / Company’s Official Chop): Affix company chop if applicable.
Download the current form - always file the version on the issuing authority's site, not a copy.
Sources
More on the forms library.