Reporting payments to non-resident individuals with Form IR623P
Learn how to file Form IR623P to report payments to non-resident individuals for services in Hong Kong.
IR623P at a glance
- Official title
- Notification of Payments to Non-resident Individuals Rendering Services
- Issued by
- Inland Revenue Department
We link the issuing authority's own index rather than hosting a copy, because the form is revised there and an out-of-date copy is worse than none.
Understanding Form IR623P Payments to Non-Resident Individuals
The Inland Revenue Department requires any person who makes a payment to a non-resident individual for services rendered in Hong Kong to report that payment using Form IR623P payments to non-resident individuals. This form is the prescribed mechanism for notifying the IRD of payments that may give rise to a Hong Kong tax liability for the non-recipient. The obligation falls on the payer, who is classified as a "prescribed person" under the Inland Revenue Ordinance (Cap. 112).
When Is Form IR623P Required
Form IR623P must be filed when a payment is made to a non-resident individual for services rendered in Hong Kong. The term "services rendered" covers a broad range of activities, including professional services, technical services, consultancy work, and any other form of personal services performed within Hong Kong's jurisdiction. The key factor is the location where the services are physically performed, not the residence of the payer or the place where the contract was signed.
The form is not required for payments to non-resident companies, which are covered by separate reporting obligations. It applies specifically to individuals who are not ordinarily resident in Hong Kong and who derive income from services performed in the territory.
Non-Resident Service Provider Tax Hong Kong
Hong Kong operates a territorial basis of taxation, meaning income sourced in Hong Kong is chargeable to tax regardless of the recipient's residence status. For non-resident service providers, this creates a direct tax liability on fees earned for services rendered within Hong Kong. The payer becomes responsible for reporting these payments to the Inland Revenue Department through Form IR623P.
The tax liability for a non-resident individual is calculated on the gross amount of the payment, unless the IRD agrees to assess on a net basis after considering allowable expenses. The standard profits tax rate for non-resident individuals is the same as for resident individuals, but the collection mechanism differs because the payer must withhold and remit the tax.
IR623P Filing Requirements
The filing requirements for Form IR623P are specific and must be followed precisely to avoid penalties. The form must be submitted to the Inland Revenue Department within 30 days of the payment being made. The submission must include:
- Full particulars of the non-resident individual, including name, address, and tax reference number if known
- Detailed description of the services rendered
- The date and amount of the payment
- The Hong Kong source of the payment
- Any contract or agreement under which the services were performed
The form is submitted to the IRD's office. The IRD may request additional information or documentation to verify the nature of the services and the residency status of the individual.
Withholding Tax Services Hong Kong
Hong Kong does not have a general withholding tax system for payments to non-residents. However, for payments to non-resident individuals for services rendered in Hong Kong, the payer must withhold tax at the time of payment and remit it to the Inland Revenue Department. This is not a formal withholding tax in the sense of a statutory rate applied to all payments; rather, the payer must calculate the estimated tax liability and withhold that amount.
The withholding obligation arises because the non-resident individual may not have a permanent establishment in Hong Kong and may not file a tax return. The payer acts as the collection agent for the IRD. The amount withheld must be paid to the IRD within 30 days of the payment, accompanied by Form IR623P.
Particulars of Payment Required
The particulars of payment that must be disclosed on Form IR623P include:
- The gross amount paid or payable to the non-resident individual
- Any deductions made from the payment, such as expenses or commissions
- The date of payment
- The currency of payment
- The method of payment, such as bank transfer, cheque, or cash
The IRD uses these particulars to assess whether the payment is properly chargeable to Hong Kong tax and to calculate the correct amount of tax due. Inaccurate or incomplete particulars may result in the IRD issuing an estimated assessment against the non-resident individual or the payer.
Tax Liability of the Non-Resident Individual
The non-resident individual remains primarily liable for the Hong Kong tax on income derived from services rendered in Hong Kong. The payer's obligation to withhold and report does not extinguish the individual's own tax liability. The non-resident individual must file a profits tax return (Form BIR54) if the IRD issues one, or may voluntarily file to claim deductions and obtain a refund if too much tax was withheld.
The IRD may assess the non-resident individual directly if the payer fails to withhold or report. In such cases, the IRD may also pursue the payer for the unpaid tax as a penalty for non-compliance.
Submission of Form IR623P
Form IR623P is submitted to the Inland Revenue Department by post or in person at the IRD's office. The form is available for download from the IRD's website. The IRD does not currently accept electronic submission of Form IR623P through the Business Tax Portal, though this may change as the department moves towards full electronic filing by 2030.
The form must be signed by the payer or an authorised representative. If the payer is a company, the form must be signed by a director, the company secretary, or another authorised officer. The IRD may reject unsigned or incomplete forms and request resubmission.
Consequences of Non-Compliance
Failure to file Form IR623P or to withhold tax from payments to non-resident individuals can result in penalties under the Inland Revenue Ordinance. The IRD may impose a penalty of up to three times the amount of tax that should have been withheld. In addition, the payer may be personally assessed for the unpaid tax.
The IRD actively monitors payments to non-resident individuals through information sharing with other tax authorities under double taxation agreements and through audits of Hong Kong businesses. Non-compliance carries significant financial and reputational risk.
Practical Steps for Compliance
To comply with the requirement to file Form IR623P, a payer should:
- Identify all payments made to non-resident individuals for services rendered in Hong Kong
- Determine the residency status of the individual by reviewing their passport, visa, or tax residence certificate
- Calculate the estimated tax liability on the payment
- Withhold the estimated tax from the payment
- File Form IR623P within 30 days of the payment
- Remit the withheld tax to the IRD at the same time
The payer should retain copies of all forms, correspondence with the IRD, and evidence of the services rendered for at least seven years, as the IRD may review the transaction during an audit.
How to fill out Form IR623P
Page one of the official form. Every field named below appears on it in the same order.
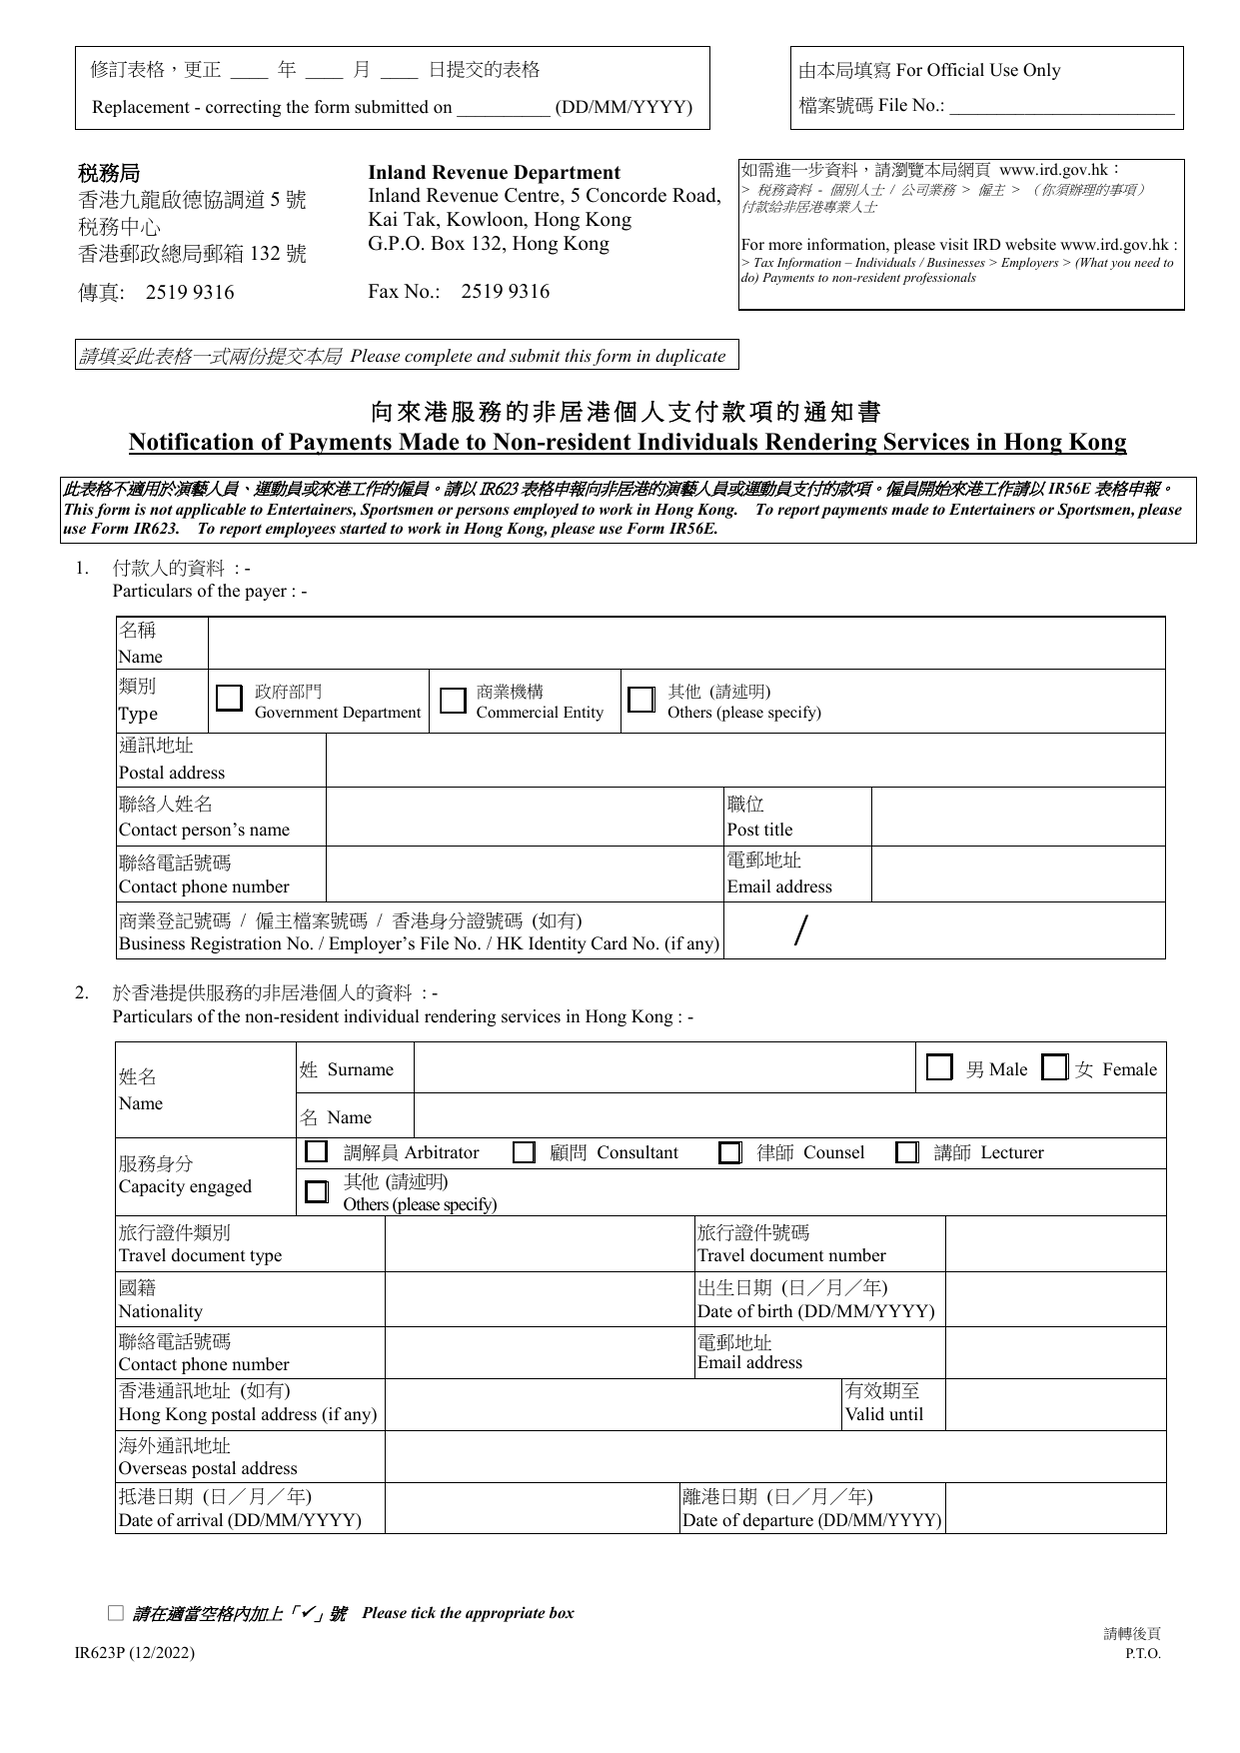
Download the current form - always file the version on the issuing authority's site, not a copy.
Sources
More on the forms library.