Reporting income of non-resident individuals with Form IR623R
Guide to filing Form IR623R for reporting Hong Kong-sourced income received by non-resident individuals.
IR623R at a glance
- Official title
- Notification of Income Received by Non-resident Individuals
- Issued by
- Inland Revenue Department
We link the issuing authority's own index rather than hosting a copy, because the form is revised there and an out-of-date copy is worse than none.
Form IR623R Income of Non-Resident Individuals
The Form IR623R income of non-resident individuals is a notification required by the Inland Revenue Department (IRD) when certain Hong Kong-sourced income is received by or on behalf of a person who is not ordinarily resident in Hong Kong. This form ensures that the IRD is informed of income streams that may be subject to Hong Kong tax, even though the recipient is not a Hong Kong resident. The obligation to file falls on the person in Hong Kong who makes the payment or who has control over the income, known as the prescribed person.
Non-Resident Income Tax Hong Kong
Hong Kong operates a territorial tax system, meaning that only income arising in or derived from Hong Kong is subject to tax. For non-resident individuals, this principle applies equally. Non-resident income tax Hong Kong is assessed on Hong Kong-sourced income, and the IRD uses Form IR623R to capture details of such income that might otherwise go unreported. The form is not a tax return itself but a notification mechanism that triggers the IRD's assessment process. The tax obligation for the non-recipient is determined separately by the IRD after reviewing the particulars provided.
IR623R Reporting Obligations
The IR623R reporting obligations apply to any prescribed person who receives or is entitled to receive income on behalf of a non-resident individual. A prescribed person includes a payer, an agent, a trustee, or any other person who has the receipt, control, or disposal of the income. The obligation is triggered when the income is Hong Kong-sourced and falls within specified categories. The prescribed person must submit the form within a reasonable time after the income is received, though the IRD may specify a particular submission deadline in individual cases. Failure to notify can result in penalties under the Inland Revenue Ordinance (Cap. 112).
Hong Kong Sourced Non-Resident Income
Hong Kong sourced non-resident income that must be reported on Form IR623R includes several categories. The most common are royalties paid for the use of intellectual property in Hong Kong, interest derived from Hong Kong sources, dividends paid by a Hong Kong company, and pensions paid from Hong Kong. The form requires the prescribed person to provide full particulars of income, including the amount, the date of receipt, the name and address of the non-resident individual, and the nature of the income. The IRD uses this information to determine whether the income is chargeable to tax and, if so, to issue an assessment.
Types of Income Requiring Notification
The specific types of income that trigger a Form IR623R filing are set out in the Inland Revenue Ordinance. These include:
- Royalties: Payments for the use of or right to use any copyright, patent, trademark, design, or other intellectual property in Hong Kong.
- Interest: Interest paid by a Hong Kong resident or from a Hong Kong source to a non-resident individual.
- Dividends: Dividends paid by a Hong Kong company to a non-resident shareholder.
- Pensions: Pensions paid from Hong Kong to a non-resident individual.
- Other income: Any other income arising in Hong Kong that is received by a non-resident individual, such as fees for services performed in Hong Kong or rental income from Hong Kong property.
The prescribed person must report each category separately on the form, providing the gross amount before any deductions. The IRD may also require supporting documents, such as contracts or invoices, to verify the nature of the income.
Who Must File Form IR623R
The responsibility to file Form IR623R rests with the prescribed person in Hong Kong. This is typically the person who makes the payment to the non-resident individual or who has control over the income. For example, if a Hong Kong company pays royalties to a non-resident inventor, the company must file the form. If a Hong Kong trustee holds income for a non-resident beneficiary, the trustee must file. The prescribed person must ensure that the form is completed accurately and submitted to the IRD. The non-resident individual does not file the form themselves; the obligation is on the Hong Kong-based person.
Information Required on Form IR623R
The form requires the prescribed person to provide detailed particulars of income. This includes:
- The name, address, and tax identification number of the non-resident individual.
- The amount of income received, in Hong Kong dollars.
- The date or dates on which the income was received.
- The nature of the income (royalty, interest, dividend, pension, or other).
- The source of the income in Hong Kong.
- The name and address of the payer or person who made the payment.
- Any withholding tax or other deductions made from the income.
The prescribed person must also declare that the information provided is true and correct. The IRD may request additional information if the particulars are incomplete or unclear.
Submission Deadline and Penalties
The IRD does not prescribe a fixed submission deadline for Form IR623R in all cases. The prescribed person should submit the form as soon as practicable after the income is received. In practice, the IRD may issue a notice requiring the form to be filed within a specified period, often 30 days. Failure to submit the form without reasonable excuse may result in a penalty of up to HK$10,000 under section 80 of the Inland Revenue Ordinance. The IRD may also assess additional tax if the income is found to be chargeable and has not been reported.
Relationship to Other IRD Forms
Form IR623R is one of several forms used to report payments to non-residents. It is distinct from Form IR623, which is used to notify the arrival of non-resident entertainers or sportsmen, and Form IR623P, which reports payments to non-resident individuals for services rendered in Hong Kong. The IR623R is specifically for income such as royalties, interest, dividends, and pensions, rather than for services. If the income falls into multiple categories, the prescribed person should use the form that best matches the primary nature of the income or seek guidance from the IRD.
Obtaining and Filing the Form
Form IR623R is available from the Inland Revenue Department's forms index at https://www.ird.gov.hk/eng/paf/bus.htm. The form can be completed manually or electronically and submitted by post or in person to the IRD's office. The IRD does not currently mandate electronic filing for this form, but the department encourages electronic submission through its eTAX portal where possible. The prescribed person should retain a copy of the completed form and any supporting documents for their records.
How to fill out Form IR623R
Page one of the official form. Every field named below appears on it in the same order.
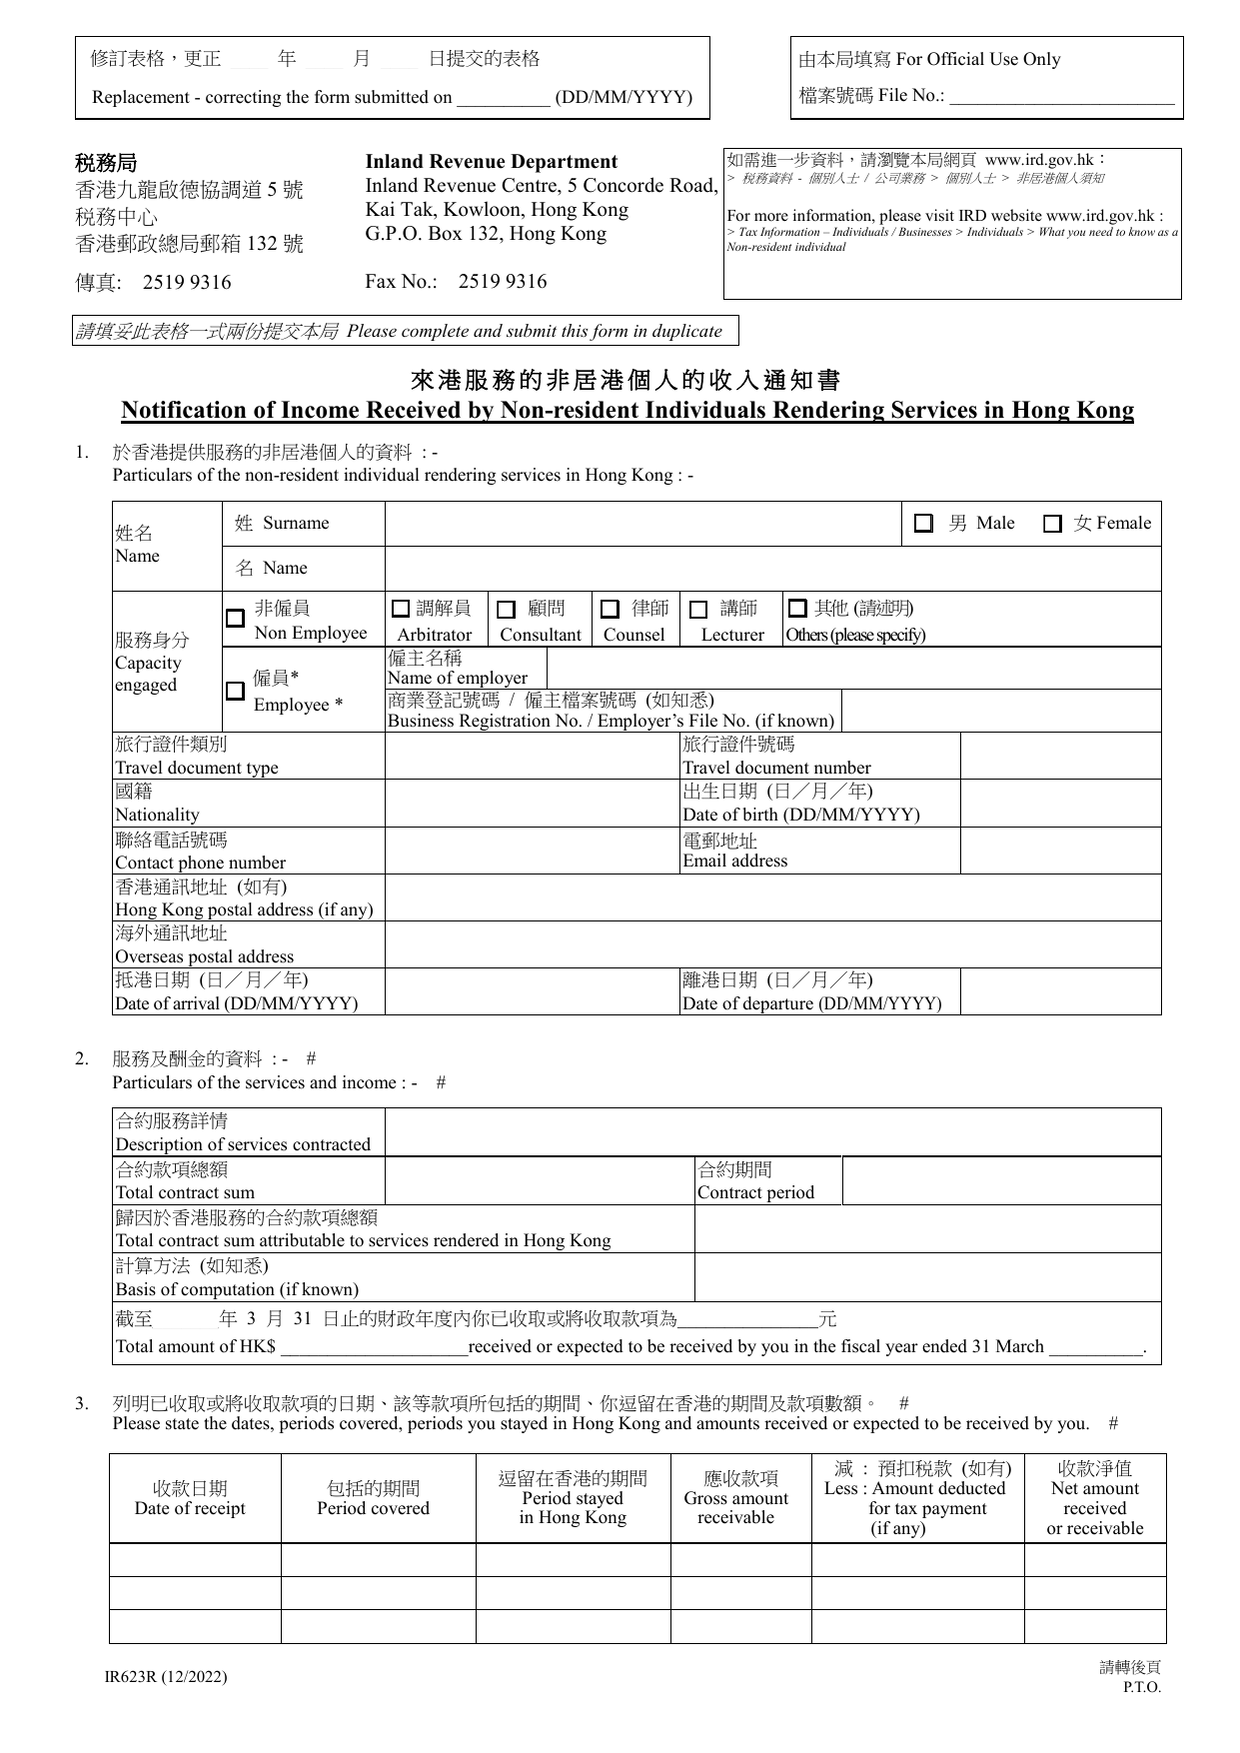
Download the current form - always file the version on the issuing authority's site, not a copy.
Sources
More on the forms library.