Form NAC4 Hong Kong: Notice of Change to Your Company's Accounting Reference Date
How to file Form NAC4 to alter your Hong Kong company's accounting reference date, including fee, deadline, and restrictions.
NAC4 at a glance
- Official title
- Notice of Alteration of Accounting Reference Date
- Issued by
- Companies Registry
- e-Filing
- Available
We link the issuing authority's own index rather than hosting a copy, because the form is revised there and an out-of-date copy is worse than none.
Form NAC4 Hong Kong: Notice of Alteration of Accounting Reference Date
Form NAC4 is the specified form for notifying the Companies Registry that a company has changed its accounting reference date. The accounting reference date is the date on which a company’s financial year ends. Altering it shifts the company’s annual return cycle and the deadlines for filing its annual return (Form NAR1) and its profits tax return (BIR51).
What Is the Accounting Reference Date?
Every Hong Kong company incorporated under the Companies Ordinance (Cap. 622) has an accounting reference date. It determines the end of the company’s financial year. For a newly incorporated company, the accounting reference date is the last day of the month in which the anniversary of its incorporation falls. The company may change this date by filing Form NAC4 with the Companies Registry.
The accounting reference date also sets the return date for the annual return. The annual return must be filed within 42 days after the return date. If the accounting reference date changes, the return date moves accordingly. File the NAC4 before the annual return for the new period becomes due.
NAC4 Accounting Reference Date Hong Kong: Required Information
The form NAC4 accounting reference date Hong Kong filing requires the following particulars:
- The company’s name and its Companies Registry number (CR number)
- The current accounting reference date (the date that is being changed)
- The new accounting reference date (the date the company wants to adopt)
- The reason for the alteration (for example, to align with a group parent company’s financial year)
- The signature of a director or the company secretary of the company
Complete the form in English or Chinese. If the company is a registered non-Hong Kong company, an authorised representative must sign.
Hong Kong Change Financial Year End Form: Filing Fee and Deadline
File the Hong Kong change financial year end form with the Companies Registry before the annual return for the new accounting reference period is due. There is no statutory deadline for filing the NAC4 itself, but the alteration takes effect only when the Companies Registry registers the notice. If the company files the NAC4 after the annual return for the new period has become due, the Registry may reject the notice.
The registration fee for filing Form NAC4 is HK$105. Pay it at the time of submission. The fee is the same whether the form is filed electronically through the e-Services portal or on paper.
NAC4 Filing Requirements: Restrictions on Alteration
A company cannot extend its accounting reference period to more than 18 months without special justification. The Companies Ordinance (Cap. 622) allows an accounting reference period of up to 18 months only in the first accounting period after incorporation. For subsequent alterations, the period must not exceed 18 months unless the company can demonstrate a valid reason, such as a change in the group’s financial reporting cycle.
A company also cannot alter its accounting reference date if the alteration would cause the company to have two accounting reference dates in the same financial year. The new date must fall within the same financial year as the old date, or the company must file a separate notice for each alteration.
Alter Accounting Reference Date Hong Kong: Rejection Reasons
The Companies Registry may reject a Form NAC4. Common rejection reasons:
- Incomplete particulars: the form must include the company name, CR number, old and new dates, and the reason for the alteration. Missing any of these items will cause rejection.
- Invalid date range: the new accounting reference date must not extend the period to more than 18 months without special justification. If the period exceeds 18 months and no justification is provided, the Registry will reject the form.
- Missing signature: the form must be signed by a director or the company secretary. If the signature is missing or the signatory is not an authorised officer, the Registry will reject the form.
- Duplicate filing: if the company has already filed a NAC4 for the same alteration, the Registry may reject the duplicate.
If the Registry rejects the form, correct the error and resubmit. The registration fee is not refunded on rejection.
Relationship to Form NAR1 and the Annual Return
The accounting reference date determines the return date for the annual return. The annual return (Form NAR1) must be filed within 42 days after the return date. If the company alters its accounting reference date, the return date changes accordingly. File the NAC4 before the annual return for the new period is due. If the company files the NAC4 after the annual return has become due, the Registry may reject the NAC4 and the company may face late filing penalties for the NAR1.
Relationship to Form NAC3 and Statement of Revision
Form NAC3 is used to file a statement of revision of financial statements. If a company alters its accounting reference date and subsequently revises its financial statements, it may need to file Form NAC3. The NAC4 and NAC3 are separate forms with different purposes. The NAC4 changes the accounting reference date; the NAC3 revises previously filed financial statements.
Filing Channels
The Companies Registry accepts Form NAC4 through two channels:
- Electronic filing through the e-Services portal at https://www.eregistry.gov.hk/
- Paper filing by post or in person at the Companies Registry counter
Electronic filing is faster and allows the company to receive confirmation of registration sooner. The registration fee is the same for both channels.
Where to Find the Form
The official Form NAC4 is available on the Companies Registry’s specified forms index at https://www.cr.gov.hk/en/forms/specified.htm. The Registry revises forms periodically. Download the current version from the official site rather than using a copy from another source. A stale form may be rejected.
How to fill out Form NAC4
Page one of the official form. Every field named below appears on it in the same order.
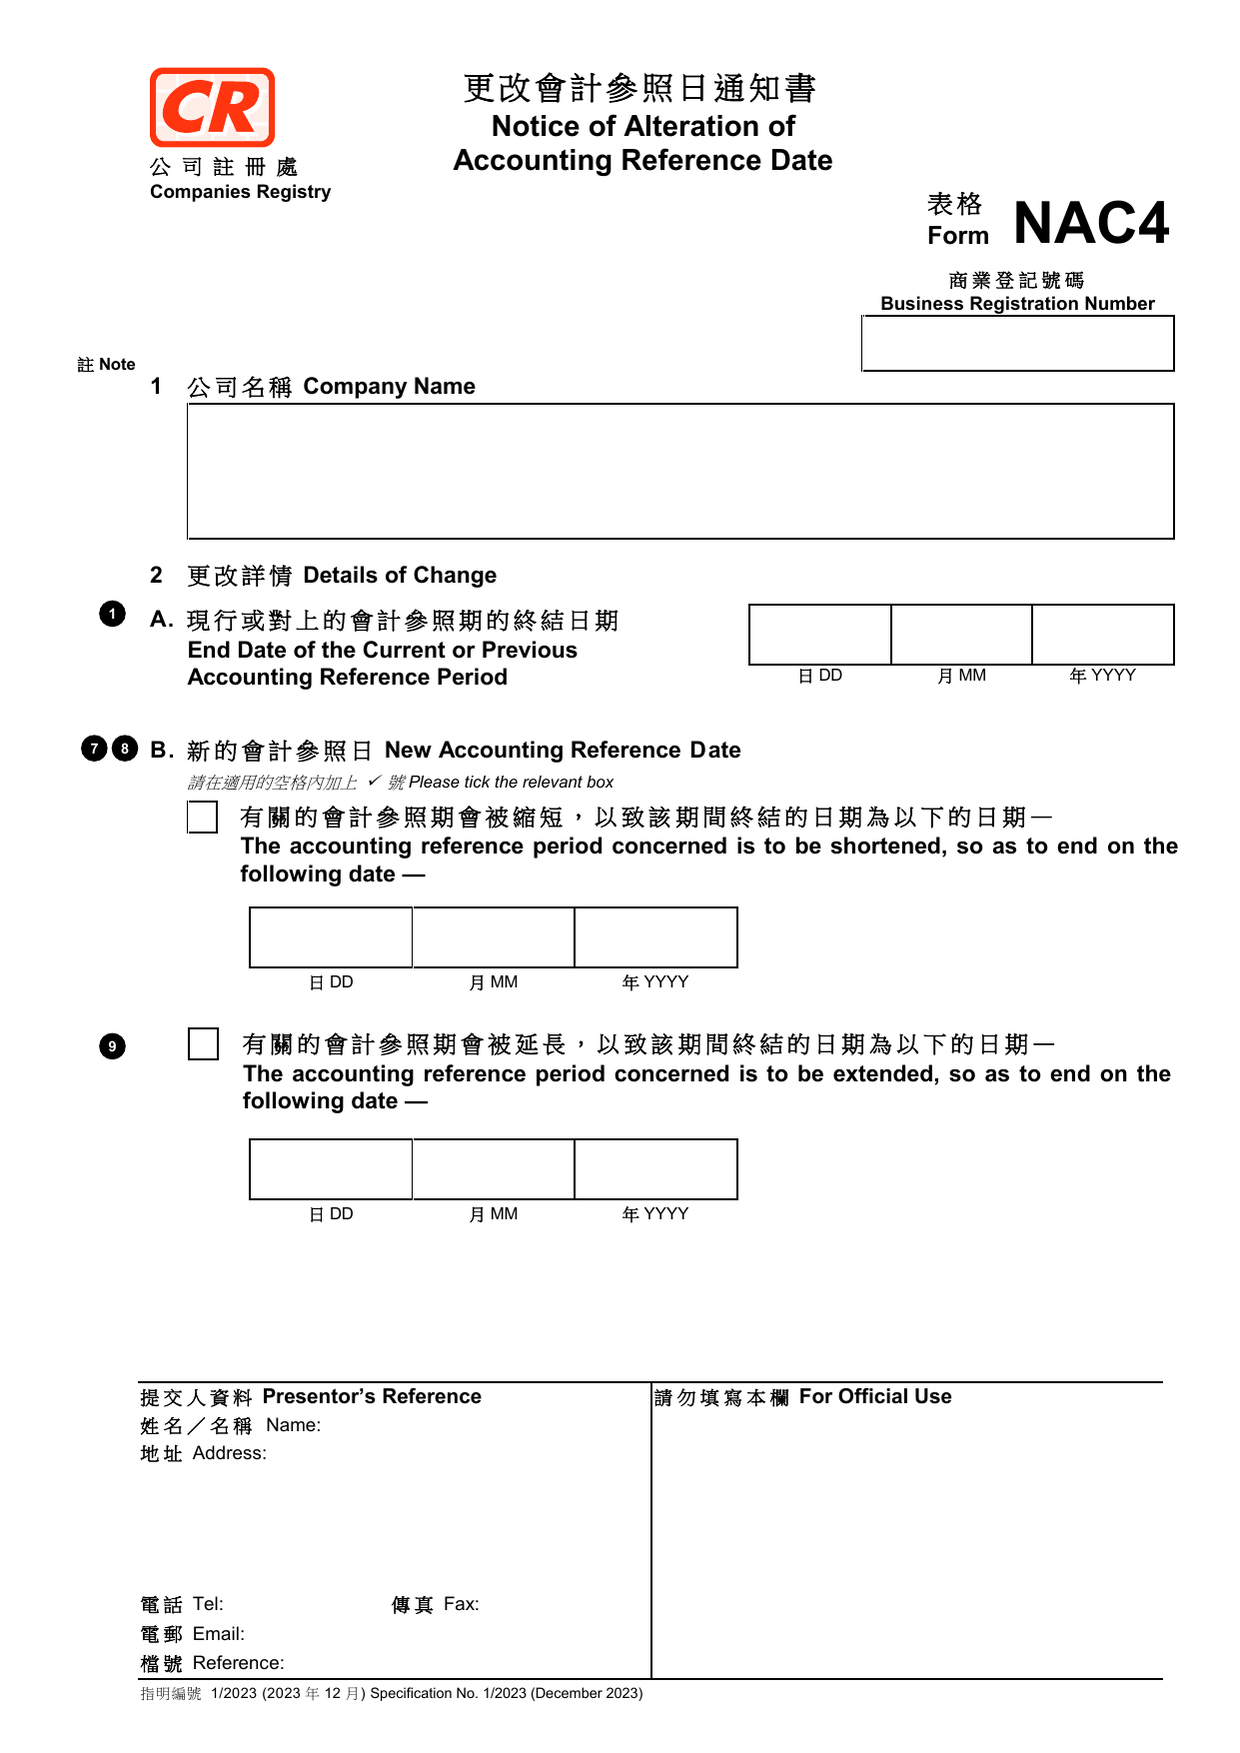
商業登記號碼 Business Registration Number
填報由稅務局商業登記署發出的商業登記號碼,即商業登記證號碼的首 8 位數字。「-」後的數字無須填寫。2023年12月27日或之後成立的公司,此號碼亦見於公司註冊證明書。
1 公司名稱 Company Name
填寫公司的全名(中英文,如公司有英文名稱)。
2 更改詳情 Details of Change
A. 現行或對上的會計參照期的終結日期 End Date of the Current or Previous Accounting Reference Period
填寫該會計參照期原本的終結日期(日/月/年)。「對上的會計參照期」指緊接現行會計參照期之前的那個期間。
B. 新的會計參照日 New Accounting Reference Date
在兩個選項中選擇一個並加上剔號:
- 縮短:剔選此項,並填寫新的終結日期。該期間會在新會計參照日首次出現時終結。
- 延長:剔選此項,並填寫新的終結日期。該期間會在新會計參照日第二次出現時終結。注意:延長後的期間不得超過18個月。
C. 指明新的會計參照日的董事決議的日期 Date of the Directors’ Resolution Specifying the New Accounting Reference Date
填寫董事通過決議指明新會計參照日的日期(日/月/年)。公眾公司或擔保有限公司須在該日期後的15日內交付本表格。
3 在五年內延長會計參照期
Extension of Accounting Reference Period within Five Years
如果選擇了延長會計參照期,且該較早前的會計參照期是在指明新會計參照日前的5年內終結的,則必須剔選以下其中一個方格:
- 方格一:公司未曾就該5年內的較早前會計參照期指明新日期以延長該期間。
- 方格二:公司曾就該5年內的較早前會計參照期指明新日期以延長該期間,但是次新日期是為了與其控權公司的會計參照日同步。
- 方格三:公司曾就該5年內的較早前會計參照期指明新日期以延長該期間,但是次指明已獲成員決議批准。
5 簽署 Signed
簽署 Signed:必須由一名董事或公司秘書簽署(請刪去不適用者)。未簽妥的表格將被拒絕。
姓名 Name:填寫簽署人的姓名。
日期 Date:填寫簽署日期(日/月/年)。
提交人資料 Presentor's Reference
填寫提交人的姓名/名稱、地址、電話、傳真、電郵及檔號。除非有特別事項,否則無須另加附函。
Download the current form - always file the version on the issuing authority's site, not a copy.
Sources
More on the forms library.