Form NN1 Non-Hong Kong Company Registration Hong Kong: Requirements and Filing Steps
Register a non-Hong Kong company in Hong Kong using Form NN1. Learn the required documents, fee and ongoing compliance obligations.
NN1 at a glance
- Official title
- Application for Registration as Registered Non-Hong Kong Company
- Issued by
- Companies Registry
- Deadline
- Within one month of establishing a place of business
- e-Filing
- Available
We link the issuing authority's own index rather than hosting a copy, because the form is revised there and an out-of-date copy is worse than none.
Form NN1 Non-Hong Kong Company Registration Hong Kong
Required Documents and Information for Form NN1
A foreign company establishing a place of business in Hong Kong files Form NN1 non-Hong Kong company registration Hong Kong with the Companies Registry under Part 16 of the Companies Ordinance (Cap. 622). Approval records the company as a registered non-Hong Kong company. File the form together with IRBR2 , the notice to the of the Inland Revenue Department , so the company obtains a Business Registration Certificate at the same time.
Form NN1 requires the company’s name, its proposed registered office address in Hong Kong, and the full particulars of every director and the company secretary. The registered office must be a physical address. A post office box is not acceptable. The company must also appoint an authorised representative: a person resident in Hong Kong authorised to accept service of process and notices on the company’s behalf. State that representative’s particulars, including a Hong Kong residential or business address, in the form.
Certified True Copies and Constitutional Documents
Every application under Form NN1 must be accompanied by certified copies of documents from the company’s place of incorporation. The list:
- A certified true copy of the company’s certificate of incorporation, or equivalent document evidencing its existence as a body corporate.
- A certified true copy of the company’s constitutional documents , its memorandum and articles of association, or the equivalent governing instrument.
- A certified true copy of its register of directors.
- A certified true copy of its register of secretaries, if applicable.
- A certified true copy of its register of members or a statement of its shareholders.
A notary public, a solicitor, or a similar qualified person in the jurisdiction of incorporation must certify these copies as true. If the documents are not in English or Chinese, provide a certified translation.
The Companies Registry reviews the documents to ensure the company’s name is not the same as or too similar to an existing Hong Kong company or registered non-Hong Kong company. An objectionable name may trigger a requirement to change it before the Registry proceeds.
NN1 Filing Fee Hong Kong
The NN1 filing fee Hong Kong is HK$1,945. That covers the initial registration and the issue of a Certificate of Registration. The fee is subject to change; confirm the current amount on the Companies Registry’s specified forms index before submitting.
The accompanying IRBR2 notice attracts a separate fee for the Business Registration Certificate. The charges an annual fee of HK$2,150. Pay both fees together when lodging the application.
Submit electronically through the Companies Registry’s e-Services portal or by paper. Electronic filing generally means faster processing and lower fees for certain transactions, but the registration fee for NN1 remains the same regardless of channel.
Register Non-Hong Kong Company Hong Kong
Part 16 of Cap. 622 governs the process to register non-Hong Kong company Hong Kong. It applies to any body corporate incorporated outside Hong Kong that establishes a place of business in Hong Kong. “Place of business” includes a share transfer or share registration office, a branch office, a representative office, or any other premises from which the company carries on business.
Once registered, the company is a “registered non-Hong Kong company”. Ongoing reporting obligations under Part 16 apply. File an annual return (Form NN3) within 42 days after each anniversary of registration. The annual return must include a copy of the company’s financial statements for its most recent financial year, prepared in accordance with the accounting standards of its place of incorporation and audited if the law of that place requires it.
Maintain a registered office in Hong Kong at all times. Notify the Registry of any change to the registered address using Form NN9. Report any change in the particulars of a director or company secretary on Form NN6.
Branch versus Subsidiary for Tax Purposes
A registered non-Hong Kong company is, for legal purposes, a branch of the foreign entity. It is not a separate legal person. A subsidiary is a separate Hong Kong company incorporated under Cap. 622. The distinction matters for tax.
A branch is taxed on profits attributable to its Hong Kong operations, calculated under the same rules as those for a Hong Kong resident company , the Profits Tax rate for corporations is 16.5%. The branch’s worldwide assets and liabilities remain with the foreign parent. The branch itself cannot distribute dividends the way a subsidiary can. A subsidiary, as a separate legal entity, can retain profits and pay dividends to its shareholders. That may offer more tax planning flexibility depending on the parent company’s jurisdiction.
Seek professional advice on the tax implications in both Hong Kong and the home jurisdiction before deciding which structure to adopt.
Part 16 Registration Hong Kong
Registration under Part 16 registration Hong Kong is governed by sections 775 to 789 of the Companies Ordinance (Cap. 622). The table below summarises the key requirements.
| Requirement | Details |
|---|---|
| Application form | NN1 (with IRBR2 for business registration) |
| Accompanying documents | Certified true copies of certificate of incorporation, constitutional documents, register of directors/secretaries, register of members |
| Authorised representative | A person resident in Hong Kong authorised to accept service |
| Registered office | A physical address in Hong Kong |
| Registration fee | HK$1,945 (subject to change; confirm on the Registry’s index) |
| Business registration fee | HK$2,150 per year (subject to change) |
| Ongoing obligations | File annual return NN3 within 42 days of each anniversary; notify changes using NN6 (director/secretary) and NN9 (registered address) |
The Companies Registry issues a Certificate of Registration once the application is approved. Display the company’s name and place of incorporation at its registered office and at any other place of business in Hong Kong.
A registered non-Hong Kong company may maintain a branch register of members in Hong Kong. The principal register remains at the company’s place of incorporation. Keep the branch register at the registered office or at another place notified to the Registry using Form NR4.
Download the forms, including NN1 and IRBR2, from the Companies Registry’s specified forms index. The Registry revises forms periodically. Always check the current version before filing.
How to fill out Form NN1
Page one of the official form. Every field named below appears on it in the same order.
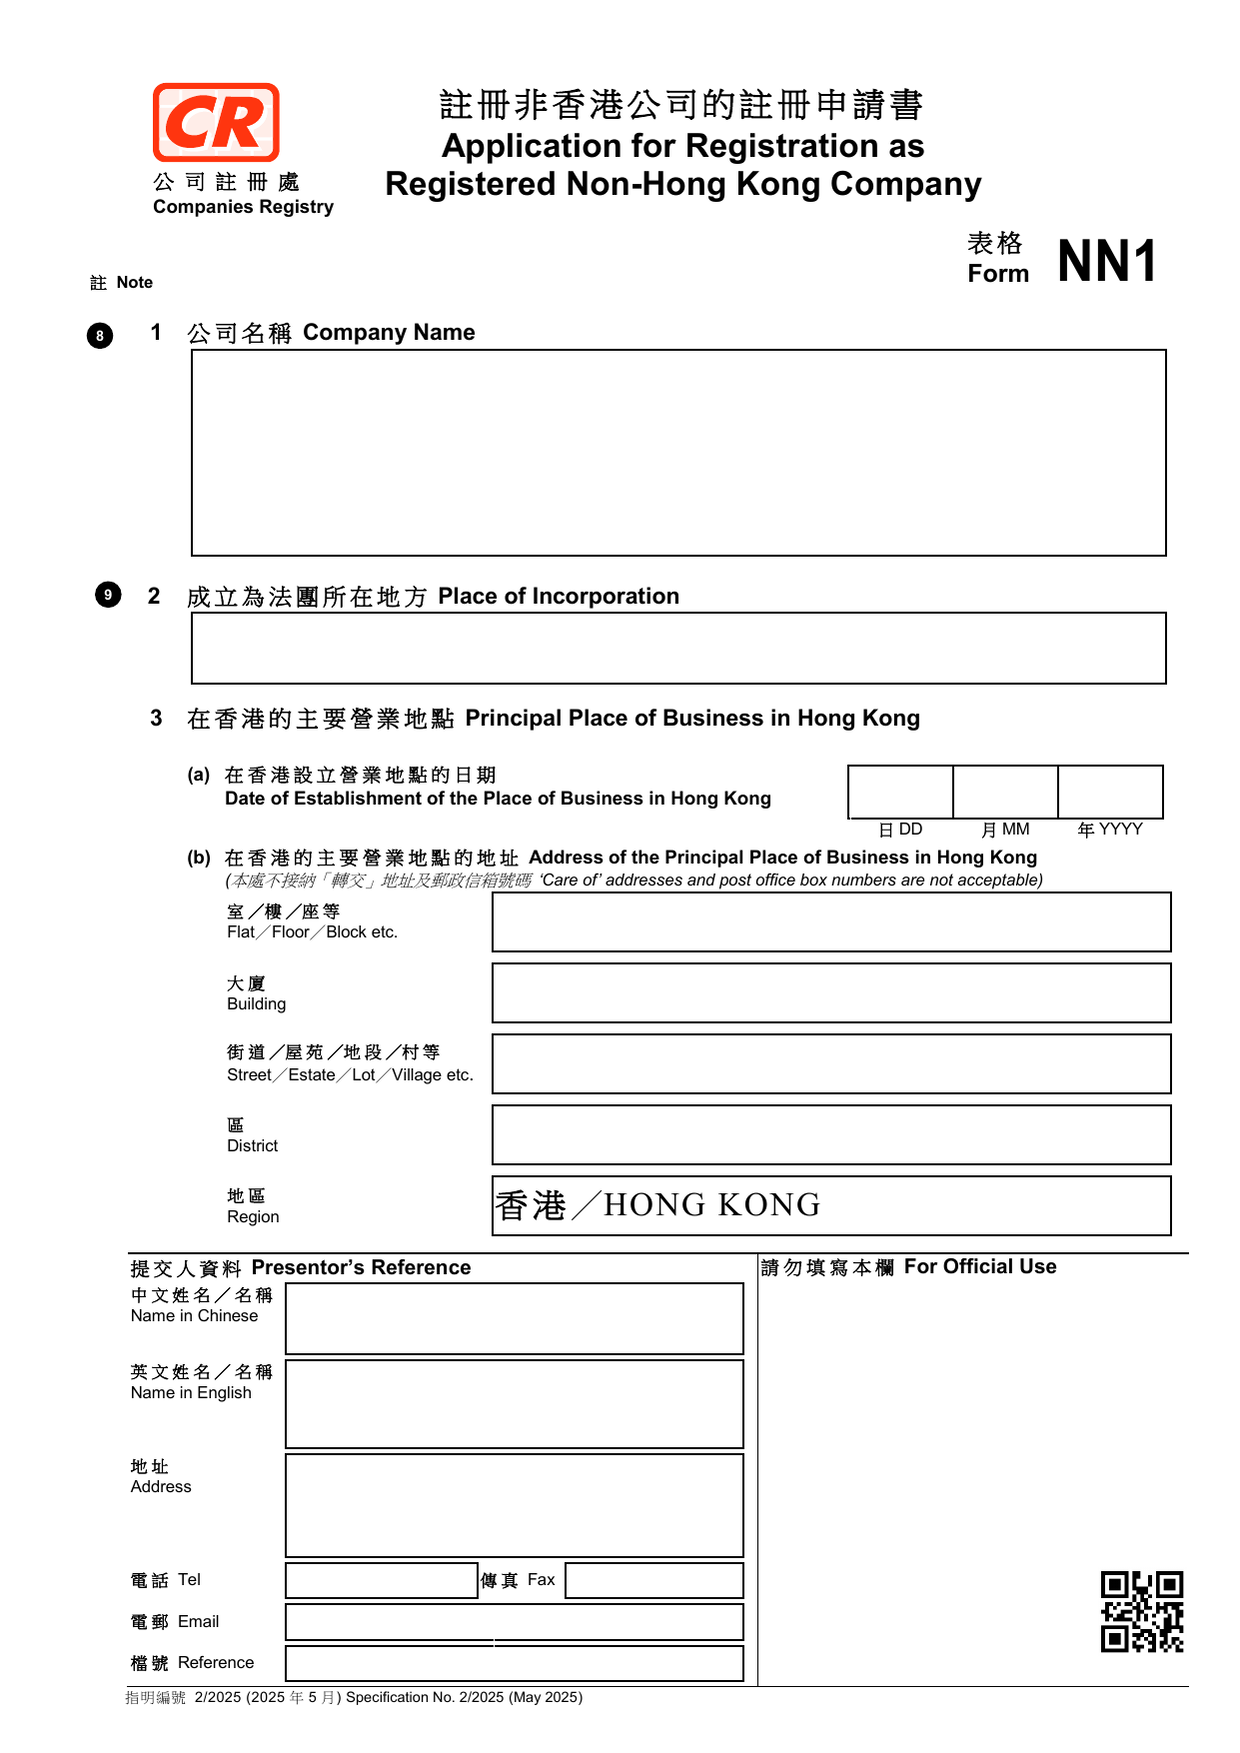
1 公司名稱 Company Name
填入擬在香港使用的公司名稱,必須與公司在其成立為法團所在地的名稱完全相同,或包含該名稱的英譯本或中譯本。名稱不可與已註冊的公司或商標混淆。
2 成立為法團所在地地方 Place of Incorporation
填入公司據以註冊的司法管轄區名稱,例如英格蘭及威爾斯、開曼群島等。須與公司的成立證明文件一致。
3 在香港的主要營業地點 Principal Place of Business in Hong Kong
(a) 在香港設立營業地點的日期 Date of Establishment of the Place of Business in Hong Kong
填入公司在香港實際開始營業的日期,格式為日、月、年(DD/MM/YYYY)。若尚未營業,則填預計開始日期。
(b) 在香港的主要營業地點的地址 Address of the Principal Place of Business in Hong Kong
填寫在香港的實際辦事處地址,分多行填入:室/樓/座、大廈、街道/屋苑/地段/村、區、地區。不接受「轉交」地址或郵政信箱號碼。 地區欄必須選取「香港」。
(c) 電郵地址 Email Address
提供該營業地點的聯絡電郵。
(d) 香港聯絡電話號碼 Hong Kong Contact Telephone Number
提供香港的聯絡電話,必須包含區號 +852。
4 在成立為法團所在地的辦事處 Offices in the Place of Incorporation
(a) 註冊辦事處地址 Address of the Registered Office
填寫公司在其成立為法團所在地的註冊辦事處完整地址,包括室/樓、大廈、街道、區/市/省/州/郵遞區號、國家/地區。不接受「轉交」地址。
(b) 主要營業地點地址 Address of the Principal Place of Business (if any)
如果公司在其成立地有另一個主要營業地點(不同於註冊辦事處),則在此填入其地址。格式同 (a)。
(c) 電郵地址 Email Address
提供該成立地辦事處的電郵。
5 在香港的獲授權代表 Authorized Representative in Hong Kong
必須指定至少一名獲授權代表,代表公司接收法律文件。可以是自然人(A 部)或非自然人(B 部)。
A. 獲授權代表 (自然人) Authorized Representative (Natural Person)
- 中文姓名/英文姓名:填寫代表的完整姓名;英文姓名分「姓氏」及「名字」兩欄。
- 香港地址:須為實際地址,不可接受「轉交」地址或郵政信箱。
- 電郵地址 (欄 12):提供代表的電郵。
- 身分識別 (欄 13):必須在獨立的 PI-NN1 頁填寫完整身分識別號碼,此處只需填寫香港身分證部分號碼(首四個字元,例如 A123) 或護照部分號碼及簽發國家/地區。常見錯誤:直接在 NN1 表格上填全號碼,必須用 PI-NN1 頁。
- 委任日期:代表獲委任的日期。
B. 獲授權代表 (非自然人) Authorized Representative (Other than Natural Person)
- 適用類別:在「律師行或律師法團」或「會計師事務所或執業法團」的方格內打 ✓。只可選一項。
- 中文名稱/英文名稱:填寫該事務所或法團的全名。
- 香港地址 (欄 14):須為其實際地址。
- 電郵地址 (欄 12):提供該代表的電郵。
- 委任日期:代表的委任日期。
續頁說明:如果同一類別的代表多於一名(例如有兩位自然人代表),必須使用表格指定的續頁 A(自然人)或續頁 B(非自然人)填報。切勿在同一行填寫兩名代表。
Download the current form - always file the version on the issuing authority's site, not a copy.
Sources
More on the forms library.