Form IR1408 CEPA requisition for copies of tax documents
Request tax documents for CEPA purposes with Form IR1408. Our guide covers the requisition process for Mainland authorities.
IR1408 at a glance
- Official title
- CEPA Requisition for Copies of Tax Documents
- Issued by
- Inland Revenue Department
We link the issuing authority's own index rather than hosting a copy, because the form is revised there and an out-of-date copy is worse than none.
Form IR1408 CEPA Requisition for Copies of Tax Documents
Form IR1408 is the application for Hong Kong residents to request certified copies of tax records from the Inland Revenue Department (IRD) for submission to Mainland authorities under the Closer Economic Partnership Arrangement (CEPA). This form provides the documentary proof required to claim CEPA preferential treatment, such as reduced tariffs or market access concessions. The IRD processes the requisition and forwards the documents directly to the relevant Mainland tax authority.
Purpose of the Form IR1408
Form IR1408 facilitates the exchange of tax information between Hong Kong and Mainland China under CEPA. A Hong Kong resident uses this form to request the IRD provide certified copies of tax documents to demonstrate tax status or tax paid to Mainland authorities. The IRD verifies the documents and transmits them to the Mainland authority named in the application. This process ensures the documents meet the authentication requirements of Mainland tax officials.
Types of Documents That Can Be Requisitioned
The form covers the tax documents a Hong Kong resident may need for CEPA-related purposes. These include:
- Tax returns: Copies of filed profits tax returns (BIR51, BIR52) or individual tax returns (BIR60) showing declared income and tax position.
- Tax assessment notices: Official IRD notices confirming the tax assessed and payable for a given year of assessment.
- Tax payment receipts: Proof of tax paid, such as payment vouchers or bank statements showing settlement of tax liabilities.
- Certificates of Resident Status: IRD documents confirming the taxpayer is a Hong Kong resident for tax treaty purposes, required under CEPA to establish eligibility for preferential treatment.
- Any other tax-related documents: The applicant can specify additional documents needed, provided they are relevant to the CEPA claim.
The requisition is limited to documents held by the IRD. The applicant must identify the specific documents required and the tax years or periods to which they relate.
Who Can Use Form IR1408
Any Hong Kong resident, individual, corporation, or partnership, needing to provide tax documents to Mainland authorities under CEPA can use this form. The applicant must be the taxpayer whose records are being requested, or an authorised representative. If a representative submits the form, they must provide evidence of their authority, such as a power of attorney or a letter of authorisation.
How to Complete the Form
Form IR1408 requires the applicant to provide:
- Personal or business particulars: Full name, Hong Kong Identity Card number or Business Registration number, and contact details.
- Tax reference number: The IRD file number or tax identification number (TIN) under which the tax documents are held.
- Details of the documents requested: A clear description of each document, including the type (e.g., tax return, assessment notice), the year of assessment, and any identifying reference numbers.
- Purpose of the request: A statement confirming the documents are required for CEPA purposes, including the specific CEPA provision or benefit being claimed.
- Mainland authority details: The name and address of the Mainland tax authority or other government body that will receive the documents.
- Supporting documents: Copies of any correspondence from the Mainland authority requesting the tax documents, or other evidence that the documents are needed for a CEPA application.
The form must be signed and dated by the applicant or their authorised representative.
Submission Process
Submit the completed Form IR1408 and required supporting documents to the Inland Revenue Department. The IRD accepts submissions by post or in person at its offices. There is no electronic filing option for this form. Retain a copy of the form and any supporting documents for your records.
Upon receipt, the IRD reviews the application to verify the applicant's identity and the relevance of the documents to CEPA. If approved, the IRD prepares certified true copies of the requested documents and forwards them to the Mainland authority specified in the form. The IRD may charge a processing fee for this service, which the applicant must pay before the documents are dispatched.
Processing Time and Fees
Processing time for Form IR1408 depends on request volume and document complexity. The IRD processes the requisition within a few weeks. Check the current processing fee with the IRD before submitting the form, as the fee may be revised periodically. The fee covers the cost of copying, certifying, and dispatching the documents.
CEPA Tax Document Hong Kong
Under CEPA, Hong Kong residents seeking preferential treatment in Mainland China, such as zero tariffs on goods or access to services markets, must provide proof of their Hong Kong resident status and, in some cases, evidence of tax paid in Hong Kong. The IRD's role is to certify that the tax documents are authentic and accurate. Form IR1408 is the mechanism for this certification request. Without the certified documents, Mainland authorities may reject the CEPA claim.
IRD Form IR1408
The Inland Revenue Department publishes Form IR1408 on its official website. The form is available for download in PDF format. Use the current version of the form, as the IRD may update it periodically. The form includes instructions for completion and a checklist of supporting documents required.
Requisition for Tax Documents
The requisition process under Form IR1408 is distinct from a general request for copies of tax documents. The form is specifically designed for CEPA-related purposes, meaning the applicant must demonstrate that the documents are needed to satisfy a requirement of Mainland authorities under the Arrangement. A general request for copies of tax records would use a different form or procedure.
CEPA Resident Status Proof
A common use of Form IR1408 is to obtain a Certificate of Resident Status. This certificate is a formal document issued by the IRD confirming that the taxpayer is a Hong Kong resident for tax purposes. Mainland authorities require this certificate as part of a CEPA application to verify that the applicant meets the residency condition. The applicant can request the certificate as part of the requisition on Form IR1408, or they may apply separately using Form IR1313A (for companies) or Form IR1314A (for individuals).
Obtain Tax Documents for CEPA
To obtain tax documents for CEPA, the taxpayer must follow these steps:
- Download and complete Form IR1408 from the IRD website.
- Gather the supporting documents, including any correspondence from the Mainland authority.
- Submit the form and supporting documents to the IRD by post or in person.
- Pay the processing fee when requested by the IRD.
- Wait for the IRD to process the request and forward the certified documents to the Mainland authority.
Allow sufficient time for processing, especially if the documents are needed for a time-sensitive CEPA application.
Obtain Tax Documents for CEAPA
The process to obtain tax documents for CEAPA is the same as for CEPA. Applicants use Form IR1408 to request certified copies of tax records from the IRD. The form is submitted with supporting documents to the IRD, which then forwards the certified documents to the relevant Mainland authority.
Supporting Documents Required
The IRD requires the following supporting documents to accompany Form IR1408:
- A copy of the applicant's Hong Kong Identity Card (for individuals) or Business Registration Certificate (for corporations).
- A copy of the correspondence from the Mainland authority requesting the tax documents, if available.
- A letter of authorisation if the application is made by a representative.
- Any other documents that the IRD may request to verify the applicant's identity or the purpose of the requisition.
Ensure all supporting documents are clear and legible.
Processing Fee
The processing fee for Form IR1408 is set by the Inland Revenue Department and is subject to change. Check the current fee on the IRD website or contact the IRD directly before submitting the form. The fee is payable upon approval of the application, and the IRD will not dispatch the documents until the fee is paid.
Forwarding to Mainland Authorities
Once the IRD has prepared the certified copies, it forwards them directly to the Mainland authority specified in the form. The IRD does not provide the documents to the applicant for onward transmission, as this could compromise the certification. Ensure the address of the Mainland authority is correct and complete.
Common Issues and How to Avoid Them
Applicants should be aware of the following common issues when using Form IR1408:
- Incomplete form: Ensure all sections of the form are completed, including the description of documents and the Mainland authority details.
- Missing supporting documents: Check the IRD's checklist and include all required documents.
- Incorrect fee: Verify the current processing fee and pay the correct amount.
- Insufficient time: Allow several weeks for processing, especially during peak periods.
If the IRD rejects the application, it will provide reasons, and the applicant may resubmit with the necessary corrections.
Related Forms and Procedures
For other CEPA-related tax matters, the taxpayer may need to use additional forms:
- Form IR1313A: Application for a Certificate of Resident Status for a corporation.
- Form IR1314A: Application for a Certificate of Resident Status for an individual.
- Form IR1297: Application for an advance ruling on a proposed transaction.
These forms are available on the IRD website and should be used as appropriate.
Contacting the Inland Revenue Department
For enquiries about Form IR1408 or the requisition process, contact the Inland Revenue Department:
- Address: Inland Revenue Department, Inland Revenue Centre, 5 Concorde Road, Kai Tak, Kowloon, Hong Kong.
- Telephone: The IRD's enquiry hotline for profits tax and individual tax matters.
- Website: https://www.ird.gov.hk
The IRD's website provides the latest version of Form IR1408, instructions, and contact details for specific queries.
How to fill out Form IR1408
Page one of the official form. Every field named below appears on it in the same order.
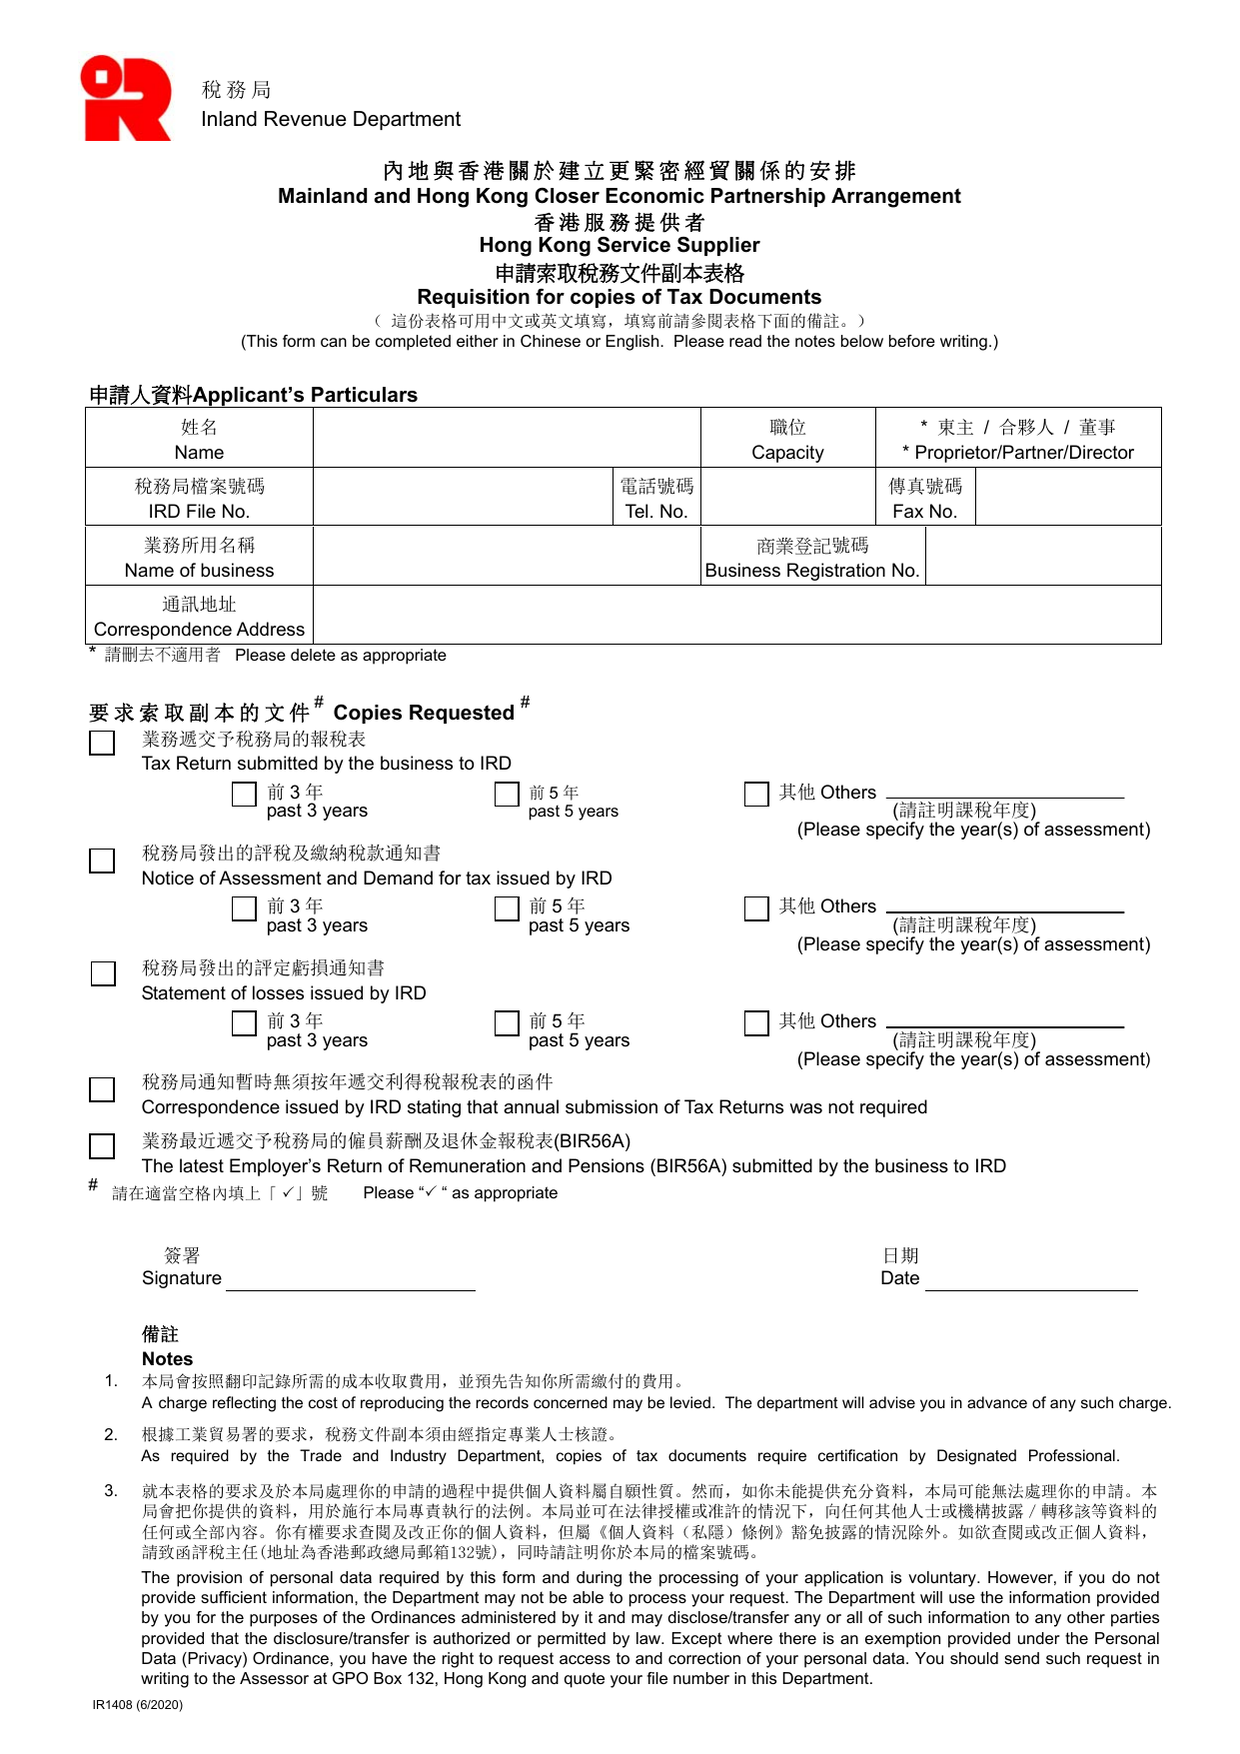
申請人資料 Applicant’s Particulars
姓名 / Name
填寫東主、合夥人或董事的姓名,與商業登記證或公司註冊文件上的姓名一致。
職位 / Capacity
圈出或保留適用的身份:東主 (Proprietor)、合夥人 (Partner) 或董事 (Director)。刪去不適用者。
稅務局檔案號碼 / IRD File No.
填寫本業務在稅務局的檔案編號。此號碼通常見於稅務局過往發出的評稅通知書或報稅表。
電話號碼 / Tel. No. 及 傳真號碼 / Fax No.
填寫申請人可被即時聯繫的電話及傳真號碼。
業務所用名稱 / Name of business
填寫商業登記證上的業務名稱。
商業登記號碼 / Business Registration No.
填寫商業登記證上的8位數字號碼。
通訊地址 / Correspondence Address
填寫收取稅務文件副本的郵寄地址。
要求索取副本的文件 Copies Requested
在每個項目旁的方格內勾選所需年份範圍。若選擇「其他 Others」,必須在括號內註明具體課稅年度(例如「2019/20」)。
-
業務遞交予稅務局的報稅表 / Tax Return submitted by the business to IRD
可選前3年、前5年,或自行註明課稅年度。 -
稅務局發出的評稅及繳納稅款通知書 / Notice of Assessment and Demand for tax issued by IRD
可選前3年、前5年,或自行註明課稅年度。 -
稅務局發出的評定虧損通知書 / Statement of losses issued by IRD
可選前3年、前5年,或自行註明課稅年度。 -
稅務局通知暫時無須按年遞交利得稅報稅表的函件 / Correspondence issued by IRD stating that annual submission of Tax Returns was not required
只可選前3年或前5年,不設「其他」選項。 -
業務最近遞交予稅務局的僱員薪酬及退休金報稅表(BIR56A) / The latest Employer’s Return of Remuneration and Pensions (BIR56A) submitted by the business to IRD
只可選取一個方格,無需指定年份。
簽署及日期 Signature and Date
由申請人(即東主、合夥人或董事)親筆簽署,並填寫簽署日期。簽署人必須與「職位」欄所選的身份一致。
備註 Notes
- 稅務局會預先通知所需繳付的翻印費用,申請人毋須在表格上填寫金額。
- 根據工業貿易署要求,取得的稅務文件副本須由指定專業人士(如會計師、律師)核證,方可作CEPA申請用途。
- 個人資料屬自願提供,但資料不足可能導致申請無法處理。如需查閱或改正個人資料,應致函香港郵政總局郵箱132號評稅主任,並註明稅務局檔案號碼。
Download the current form - always file the version on the issuing authority's site, not a copy.
Sources
More on the forms library.