Form IR1476 Engagement of Service Provider Hong Kong
Form IR1476 is used to confirm the engagement of a service provider to furnish tax returns in Hong Kong.
IR1476 at a glance
- Official title
- Confirmation for Engagement of Service Provider to Furnish Return
- Issued by
- Inland Revenue Department
We link the issuing authority's own index rather than hosting a copy, because the form is revised there and an out-of-date copy is worse than none.
Purpose and Function of Form IR1476
Form IR1476 is the Inland Revenue Department's prescribed form for a taxpayer to authorise a third party to act as its tax representative in Hong Kong. The form ir1476 engagement of service provider hong kong enables a corporation, partnership or individual to appoint a service provider - such as a certified public accountant, tax adviser or law firm - to handle correspondence with the Inland Revenue Department, receive tax returns, file submissions and manage general tax compliance matters on the taxpayer's behalf. Filing this form is not optional when the taxpayer intends to delegate tax matters: without a valid IR1476 on record, the department will communicate only with the registered taxpayer, not with any intermediary.
The form acts as a written confirmation of the engagement between the taxpayer and the service provider. It must list the full particulars of both parties, including the taxpayer's business registration number, the tax file number (where issued) and the service provider's contact details. Once processed, the Inland Revenue Department records the authorisation and sends all future correspondence to the appointed representative through the Tax Representative Portal or by post.
Completing the Form IR1476 Engagement of Service Provider Hong Kong
Any person who is liable to file a profits tax return (Form BIR51 for corporations, Form BIR52 for partnerships, or BIR54 for non-resident persons) and who wishes a third party to handle that filing must submit Form IR1476. This includes:
- Corporations incorporated in Hong Kong that engage an external accountant to prepare and submit annual profits tax returns.
- Partnerships and sole proprietors who authorise a tax agent to manage their Inland Revenue Department filings.
- Non-resident persons with Hong Kong source income who appoint a local representative.
The same form applies whether the taxpayer files on paper or through the Business Tax Portal. Even where a taxpayer has appointed a service provider for a single purpose - such as responding to a specific enquiry or filing an employer's return (IR56B) - the Inland Revenue Department requires a completed IR1476 to recognise that authority.
IR1476 Form Tax Representative Designation
The ir1476 form tax representative is the mechanism by which the taxpayer designates a specific individual or firm as the department's point of contact. The form asks for:
- The tax representative's name, business address and telephone number.
- The taxpayer's reference number and business registration number.
- A clear indication of which types of tax matters the representative is authorised to handle: profits tax, property tax, salaries tax, employer's returns, or all of the above.
The taxpayer must also sign and date the form. Where the taxpayer is a corporation, the form must be signed by a director or the company secretary; for a partnership, by a partner; for a sole proprietorship, by the proprietor. The Inland Revenue Department will not accept a form signed by the service provider on the taxpayer's behalf unless the taxpayer has granted a general power of attorney that specifically covers Inland Revenue matters.
Hong Kong Service Provider Engagement Requirements
The hong kong service provider engagement authorised by Form IR1476 has specific limits. The form does not authorise the service provider to:
- Sign statutory declarations or affidavits.
- Appear at hearings before the Board of Review or the courts.
- Receive refunds or payments from the department on the taxpayer's behalf.
For any of those actions, the taxpayer must execute a separate power of attorney under the Powers of Attorney Ordinance (Cap. 31) or give specific written instructions for each matter.
The engagement lasts until the taxpayer revokes it in writing. If the relationship ends - because the service provider resigns or the taxpayer changes advisers - the taxpayer must file a new IR1476 to appoint a replacement or notify the department that it will deal directly with the taxpayer. The department will continue to send correspondence to the previously appointed representative until it receives the updated form.
Inland Revenue IR1476 Filing Procedure
The inland revenue ir1476 form is filed by post or by hand to the Inland Revenue Department's correspondence address. There is no fee for filing the form. The department does not currently accept electronic filing of IR1476 through the Tax Representative Portal; the form must be submitted in paper.
The form is available for download from the Inland Revenue Department's website. The department recommends that the taxpayer retain a copy for its records and, if filing by post, send the form by registered post to confirm delivery.
Once received, the Inland Revenue Department processes the form and updates its records. The department does not issue a formal acknowledgement. The taxpayer should verify that future correspondence from the department is addressed to the appointed representative. If no correspondence arrives within four to six weeks, the taxpayer or the service provider may contact the department to confirm that the form has been registered.
Tax Return Service Provider Form and Compliance
The tax return service provider form IR1476 is closely linked to the filing of annual profits tax returns. When a corporation files Form BIR51 through the Business Tax Portal using the Tax Representative Portal, the Inland Revenue Department cross-references the authorisation recorded against IR1476 with the electronic submission. If no valid IR1476 is on file, the department may reject the e-filing or treat it as filed without proper authorisation, leading to correspondence being sent directly to the taxpayer rather than to the service provider.
The consequence of not filing IR1476 when engaging a service provider is practical, not penal. The Inland Revenue Department will not issue a notice of refusal or impose a fine for the omission. Instead, the department will continue to send all correspondence, including the profits tax return itself, to the taxpayer's registered address. The taxpayer must then forward the return to the service provider, creating delays that may cause the return to be filed after the due date. Late filing of a profits tax return carries penalties under the Inland Revenue Ordinance (Cap. 112), including a late surcharge of up to HK$10,000 and a potential additional assessment of up to three times the tax undercharged.
Using the Tax Representative Portal
The Inland Revenue Department's Tax Representative Portal allows an authorised service provider to view and manage a taxpayer's tax account online. Before a service provider can access the portal for the taxpayer's account, the Inland Revenue Department must have a valid IR1476 on file. The portal then enables the representative to:
- View outstanding tax returns and correspondence.
- Submit profits tax returns and employer's returns electronically.
- Respond to department enquiries.
The Business Tax Portal provides a similar service for taxpayers who file their own returns. Both portals operate under the same authorisation framework: no IR1476, no representative access.
Consequences of Incorrect or Incomplete Filing
The Inland Revenue Department will reject a Form IR1476 that is incomplete, illegible or unsigned by the correct person. Common errors include:
- Missing the taxpayer's signature.
- Failing to specify the scope of authorisation.
- Using an outdated version of the form.
If the department rejects the form, it returns it to the sender with a request to resubmit. Until the corrected form is accepted, the engagement is not recognised, and the taxpayer remains the department's sole point of contact. Service providers should therefore verify the form thoroughly before submission and follow up if no confirmation of registration is received within a reasonable period.
How to fill out Form IR1476
Page one of the official form. Every field named below appears on it in the same order.
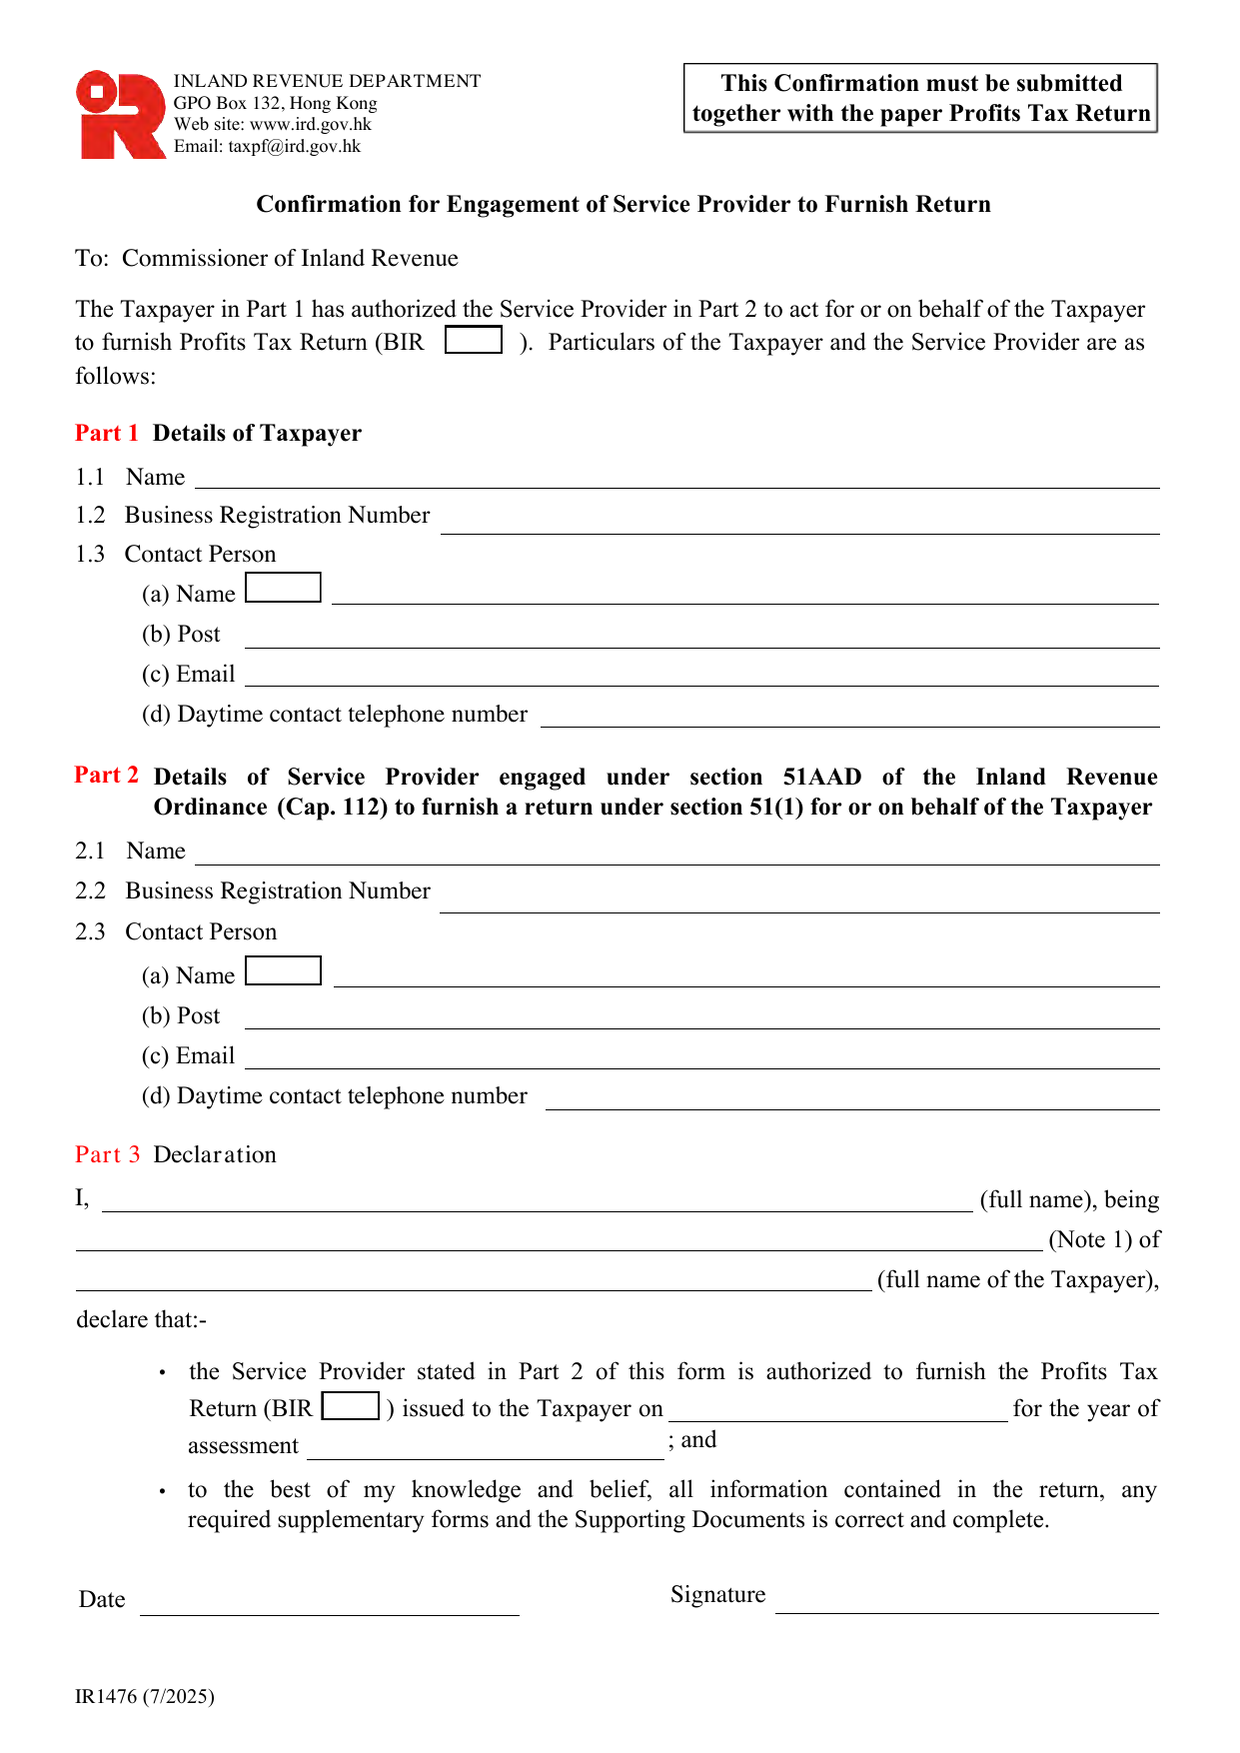
Part 1 Details of Taxpayer
1.1 Name Enter the full legal name of the taxpayer (the entity that received the Profits Tax Return).
1.2 Business Registration Number The taxpayer’s BR number. Find this on the Business Registration Certificate issued by the Inland Revenue Department.
1.3 Contact Person Provide the details of a person the IRD can contact about this confirmation. - (a) Name Full name of the contact person. - (b) Post Their job title or position within the taxpayer entity. - (c) Email A current email address. - (d) Daytime contact telephone number A phone number where they can be reached during business hours.
Part 2 Details of Service Provider
2.1 Name The full name of the firm or individual you are engaging to file the return.
2.2 Business Registration Number The service provider’s BR number, from their own BR certificate.
2.3 Contact Person Details for the person at the service provider who handles this matter. - (a) Name - (b) Post - (c) Email - (d) Daytime contact telephone number
Part 3 Declaration
This section must be completed and signed by an authorised person of the taxpayer.
I, (full name) Insert the full name of the person signing.
being (Note 1) of (full name of the Taxpayer) Insert the signer’s designation (see Note 1 below) and then the full name of the taxpayer from Part 1.1.
Note 1 is critical. The designation you enter must match the taxpayer’s legal structure: - Corporation: “secretary”, “manager”, “director”, or “investment manager” (only for an open-ended fund corporation). - Partnership (not LPF): “precedent partner of the partnership”. - Limited Partnership Fund (LPF): “general partner in the LPF”, “authorized representative as defined in section 2 of the Limited Partnership Fund Ordinance (Cap. 637)”, or “investment manager of the LPF”. - Body of persons: “principal officer of the body of persons”. - Sole proprietorship: “person”. For an executor: “executor of (the name of the deceased person)”.
The declaration text includes three blanks you must fill: - BIR ( ) Insert the return number (e.g., BIR51) that appears on the paper Profits Tax Return issued to the taxpayer. - issued to the Taxpayer on Insert the date of issue shown on that return. - for the year of assessment Insert the year of assessment (e.g., 2024/25) shown on the return.
Date The date of signing.
Signature The person named above must sign with a wet ink signature. A photocopy, fax, or scanned copy of the signed form is acceptable for submission, but the original must be retained by the service provider for at least 7 years from the date the return is filed.
Common mistakes: Entering the wrong designation from Note 1. Leaving the BIR number, issue date, or year of assessment blank. Having the wrong person sign (e.g., a service provider employee instead of the taxpayer’s authorised officer).
Download the current form - always file the version on the issuing authority's site, not a copy.
Sources
More on the forms library.